What Is a Roth IRA?
A Roth IRA is a type of individual retirement account funded with money that has already been taxed — contributions are made with after-tax dollars, so they don’t reduce your taxable income in the year you contribute. In exchange, qualified withdrawals in retirement, including all investment growth, come out completely free of federal income tax, provided the account has been open at least five years and the account holder is at least 59½.
Traditional IRA vs. Roth IRA at Withdrawal
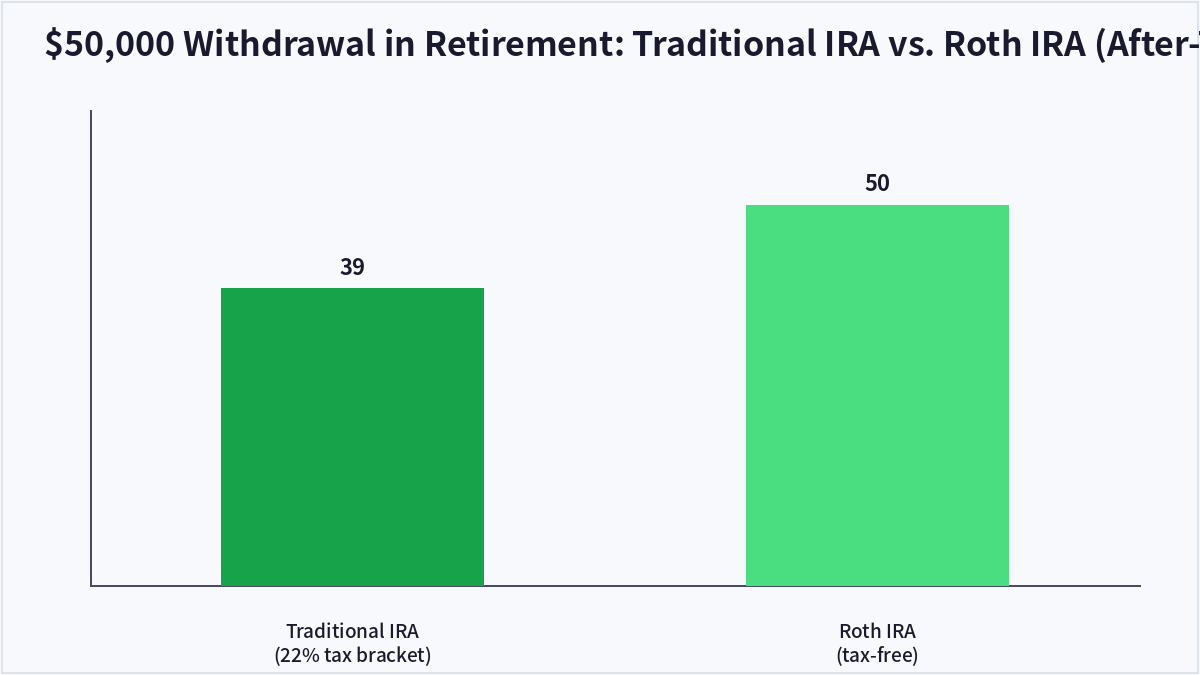
The core trade-off comes down to when you pay taxes. A traditional IRA gives you a tax deduction today but taxes withdrawals as ordinary income later — so a $50,000 withdrawal taxed at a 22% marginal rate nets only about $39,000 after tax. A Roth IRA offers no upfront deduction, but because the money was already taxed, that same $50,000 withdrawal arrives completely intact, with no additional tax owed.
Why the Roth Structure Appeals to Younger Savers
Because decades of investment growth inside a Roth IRA are never taxed, the account is particularly attractive to younger investors who expect their tax rate to be higher in retirement than it is today, or who simply want to lock in tax-free growth over a long time horizon. Roth IRAs also have no required minimum distributions (RMDs) during the original account holder’s lifetime, offering more flexibility in retirement planning.
| Feature | Traditional IRA | Roth IRA |
|---|---|---|
| Tax treatment of contributions | Often tax-deductible now | After-tax, no deduction |
| Tax treatment of withdrawals | Taxed as ordinary income | Tax-free if qualified |
| Required minimum distributions | Required starting at a set age | None during original owner’s lifetime |
Frequently Asked Questions
Is there an income limit to contribute to a Roth IRA?
Yes. Eligibility to contribute directly phases out above certain modified adjusted gross income thresholds, which are adjusted periodically — high earners sometimes use a ‘backdoor Roth IRA’ conversion strategy instead.
Can I withdraw Roth IRA contributions before retirement without penalty?
Yes, contributions (but not earnings) can generally be withdrawn at any time without taxes or penalties, since they were already taxed — though withdrawing earnings early can trigger taxes and a 10% penalty unless an exception applies.
What is a Roth conversion?
A Roth conversion involves moving funds from a traditional IRA or 401(k) into a Roth IRA, paying ordinary income tax on the converted amount now in exchange for tax-free growth and withdrawals going forward.
Are there annual contribution limits for a Roth IRA?
Yes, the IRS sets an annual dollar limit on total IRA contributions (combined across traditional and Roth accounts) that is periodically adjusted for inflation, with an additional catch-up amount allowed for those aged 50 and older.
Key Takeaways
A Roth IRA trades an upfront tax deduction for completely tax-free qualified withdrawals in retirement, making it especially valuable for investors who expect to be in a similar or higher tax bracket later in life. Its lack of required minimum distributions also adds valuable flexibility to retirement planning. This article is for informational purposes only and does not constitute investment advice.

QuantPro: AI Finds the Trade Before You Do
From AI-powered chart analysis to real-time market intelligence — everything a serious investor needs, in one platform.
- Automated AI chart analysis with precision trend timing
- Bull Radar: real-time visualization of geopolitical & economic shifts
- Live market-moving news and insights, curated for you
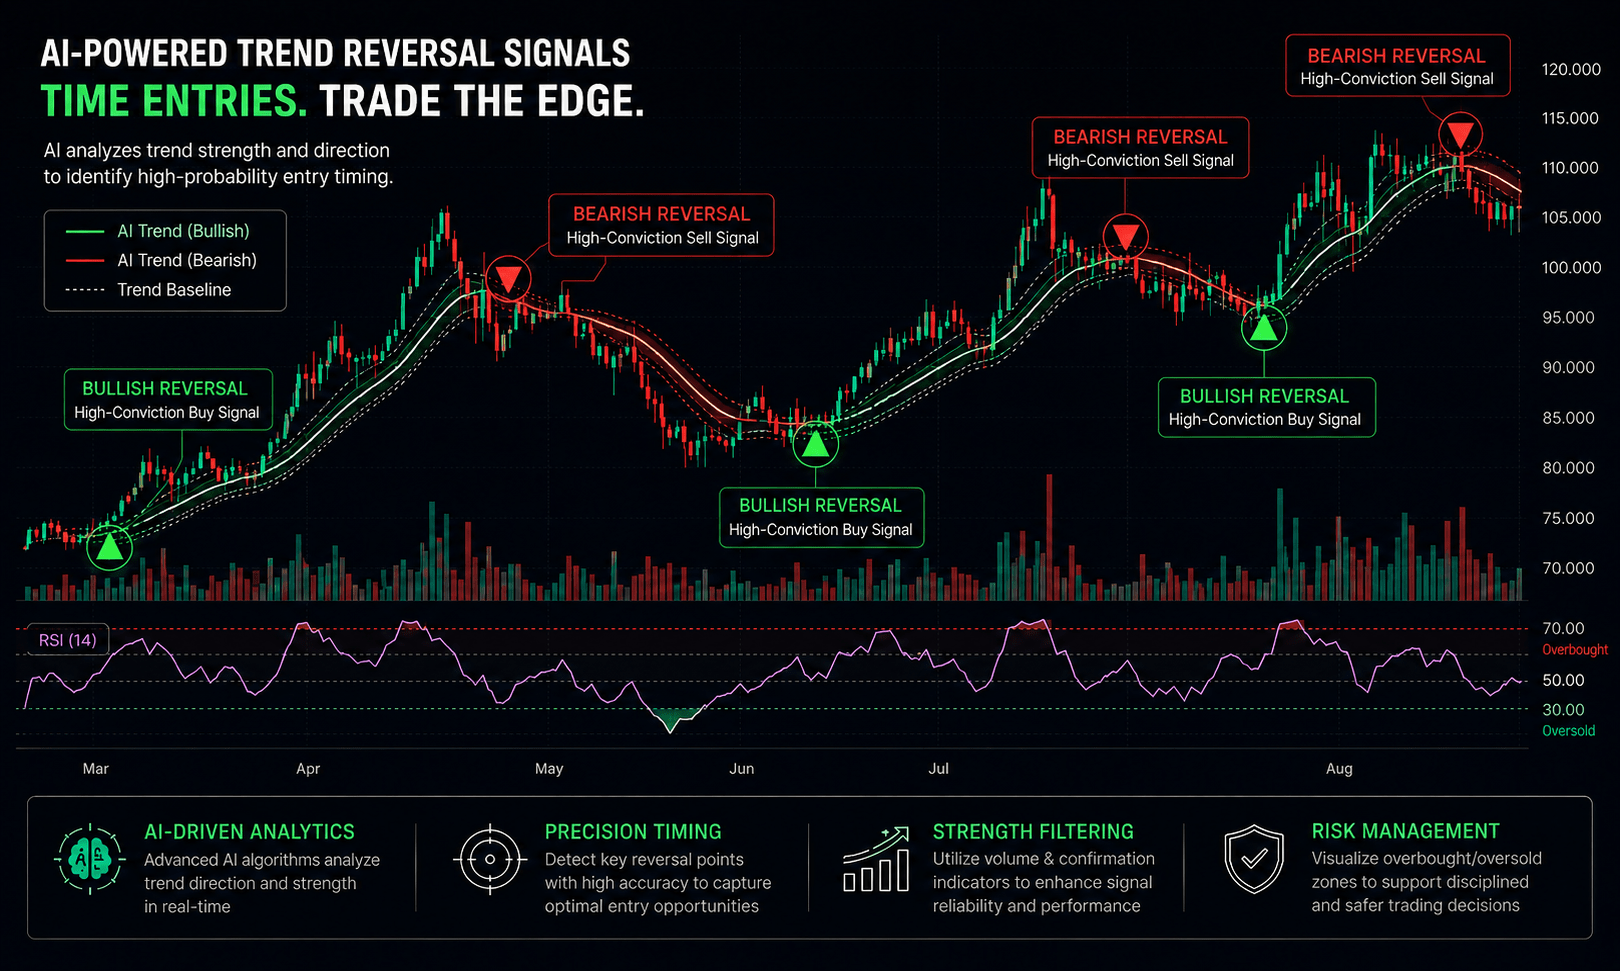
Bull Wave / Bear Wave Forecast Model
Engineered to help you read market direction and momentum faster than the crowd.
- Instantly separate bullish momentum from bearish pressure
- Pinpoint high-probability entry zones with confidence
- Chart signals clear enough for beginners, sharp enough for pros
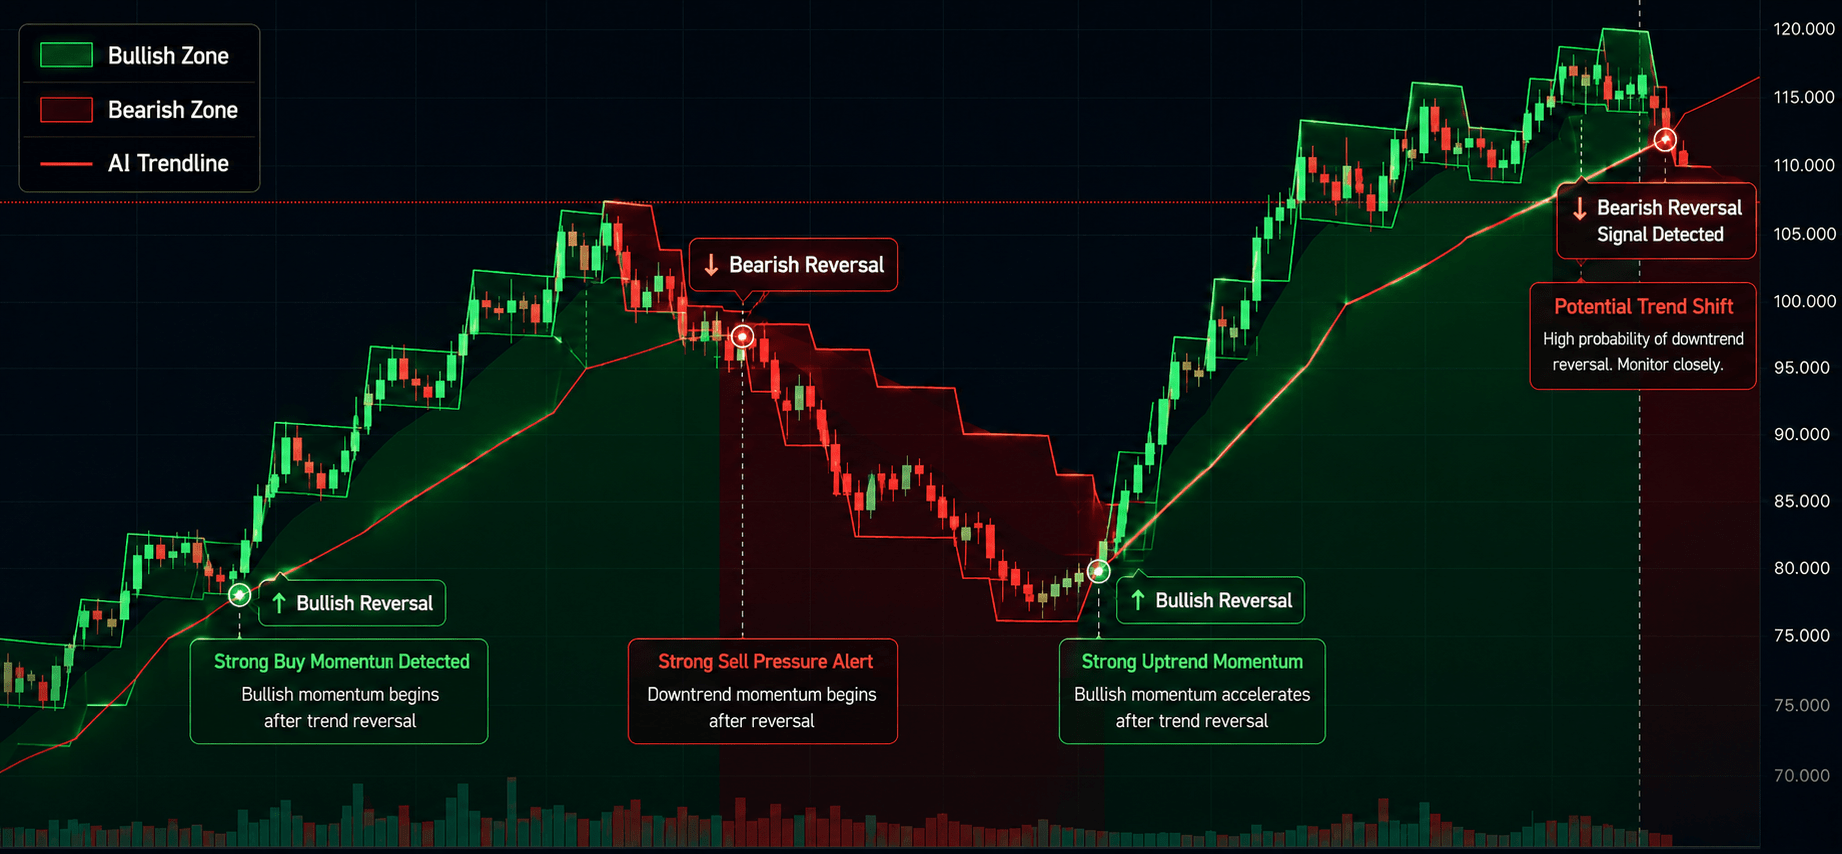
Winning Pattern Detection
Instantly surfaces the high-probability setups that repeat across the charts — a trusted edge for timing your entries and exits.
- Spot momentum building in real time
- Catch trend-reversal points before they break
- Built for active traders who need results, not theory
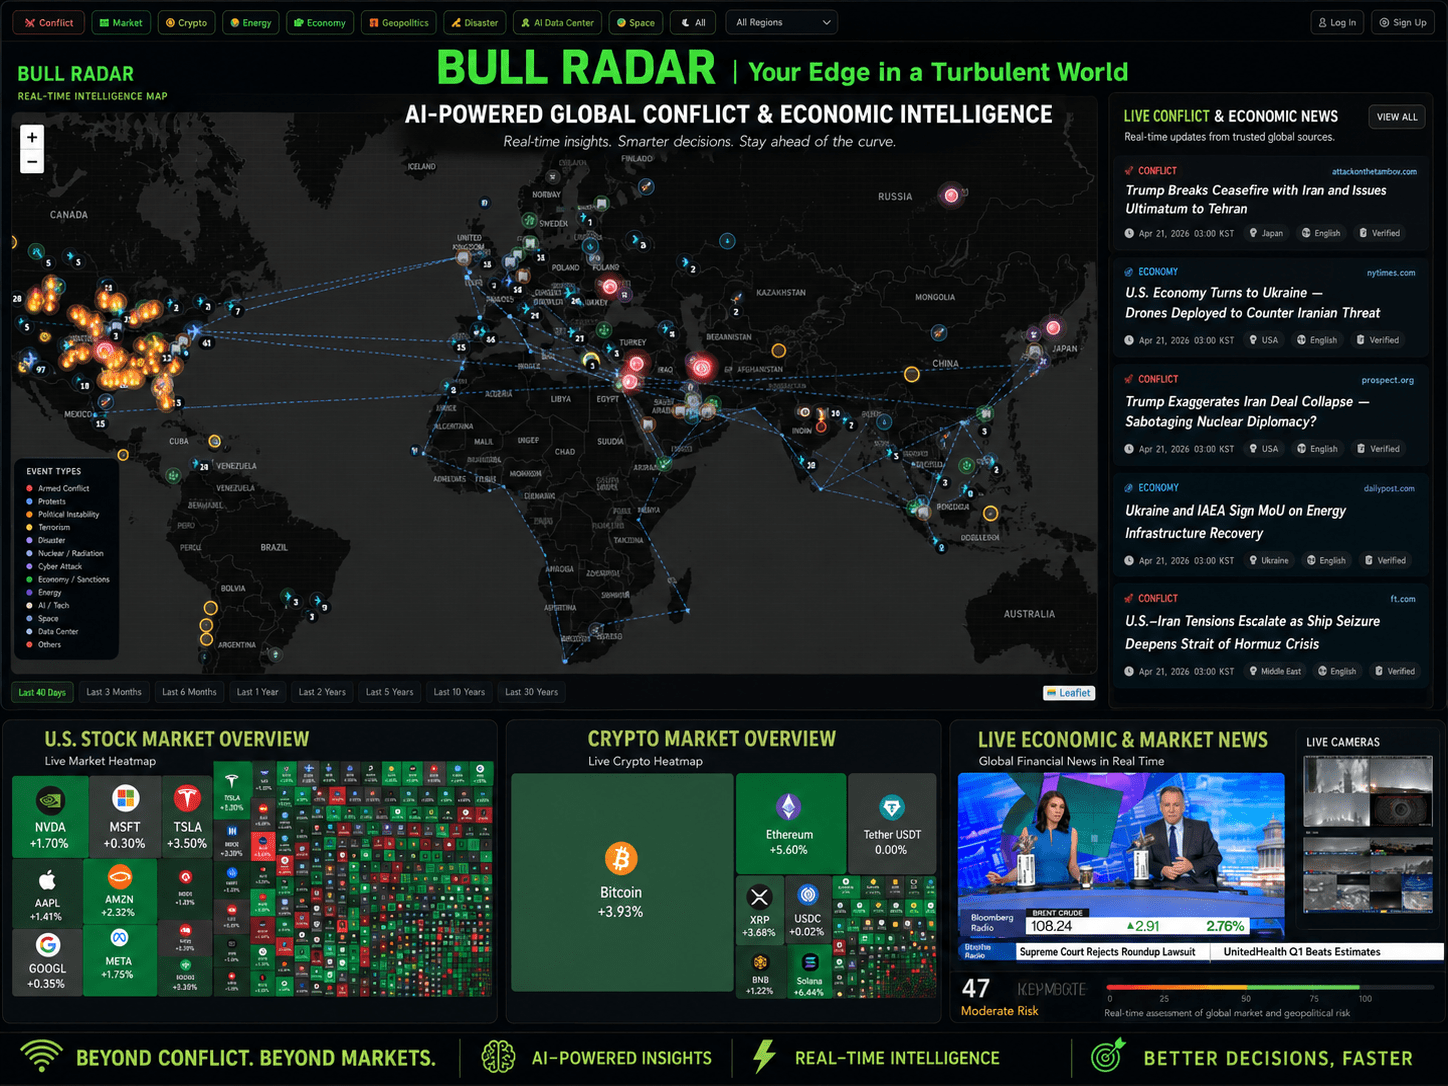
AI Live Economic Dashboard
AI analyzes real-time market data — turning complex, global investment flows into clear insight in seconds.
- Track global stock markets in real time
- See exactly which assets are strong — and which are fading
- Watch how geopolitical events move the markets
About the Author