What Put-Call Parity Is
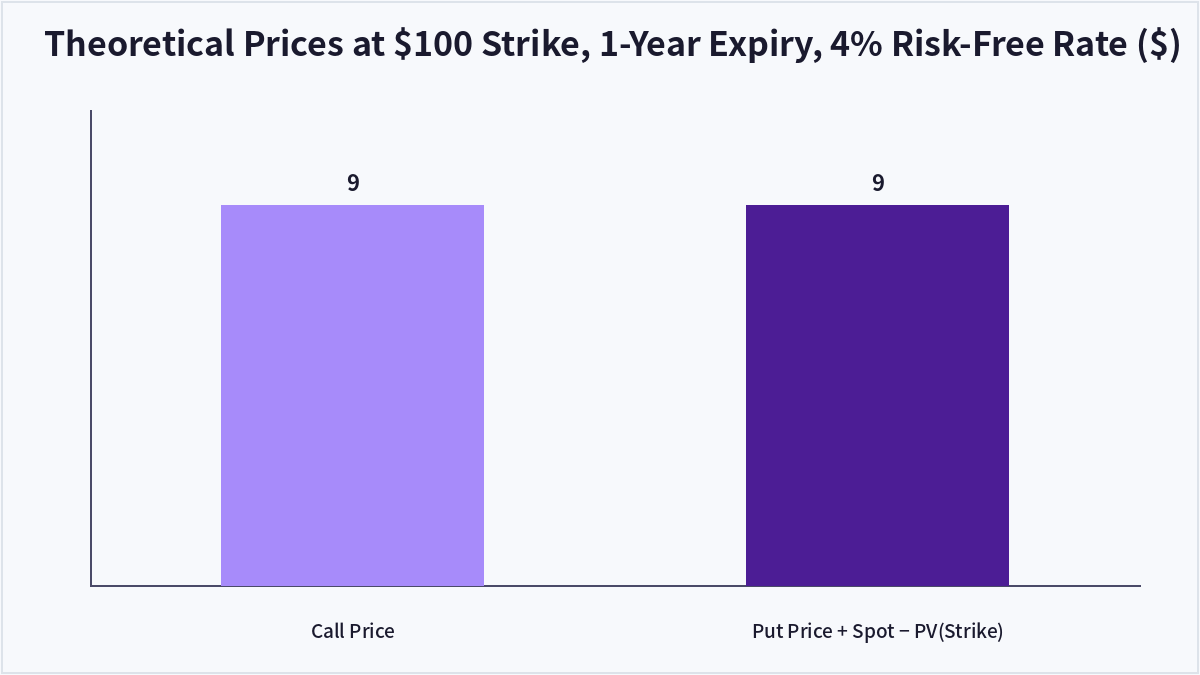
Put-call parity is a pricing relationship that must hold between a European call and a European put option with the same underlying asset, strike price, and expiration date. The formula is: call price minus put price equals the current spot price minus the present value of the strike price.
Why This Relationship Has to Hold
If this equation were ever violated, it would open a riskless arbitrage opportunity: buy the underpriced side, sell the overpriced side, and lock in a profit with no risk. Because market participants act on these opportunities immediately, the relationship holds very closely in liquid markets.
Building Synthetic Positions
This relationship lets traders combine a call option with a bond (or cash) to replicate a put option’s payoff — a ‘synthetic put’ — or combine a put option with the underlying asset to replicate a call — a ‘synthetic call.’ This is used in practice when the option a trader actually wants is illiquid or unavailable.
Limits With American-Style Options
Put-call parity holds exactly for European-style options, which can’t be exercised before expiration. American-style options, which allow early exercise, only approximate the relationship as an inequality rather than an exact equation, and dividend-paying stocks require adjusting the formula for the present value of expected dividends.
| Concept | Formula | Holds Exactly For | If Violated |
|---|---|---|---|
| Put-call parity | Call − Put = Spot − PV(Strike) | European options, no dividends (base case) | Riskless arbitrage opportunity opens up |
Frequently Asked Questions
Does put-call parity ever actually break down in real markets?
Transaction costs, taxes, and short-sale constraints can create tiny, persistent gaps, but in liquid markets any large deviation tends not to last long before it’s arbitraged away.
How does the formula change for dividend-paying stocks?
The present value of dividends expected before expiration is subtracted from the spot price to keep the relationship accurate.
Can put-call parity be used to infer implied volatility?
Not directly as a calculation, but if a call and put’s implied volatilities diverge significantly from what parity implies, it’s a signal that one of the two options may be mispriced.
Is this useful for retail investors who don’t trade arbitrage?
Even without executing arbitrage trades directly, understanding why call and put prices move together helps in designing more coherent options positions and spotting mispricing.
Key Takeaways
Put-call parity shows why call and put option prices are locked together by the threat of riskless arbitrage — a foundational relationship in options pricing theory. This article is for informational purposes only and does not constitute investment advice.

QuantPro: AI Finds the Trade Before You Do
From AI-powered chart analysis to real-time market intelligence — everything a serious investor needs, in one platform.
- Automated AI chart analysis with precision trend timing
- Bull Radar: real-time visualization of geopolitical & economic shifts
- Live market-moving news and insights, curated for you

Bull Wave / Bear Wave Forecast Model
Engineered to help you read market direction and momentum faster than the crowd.
- Instantly separate bullish momentum from bearish pressure
- Pinpoint high-probability entry zones with confidence
- Chart signals clear enough for beginners, sharp enough for pros

Winning Pattern Detection
Instantly surfaces the high-probability setups that repeat across the charts — a trusted edge for timing your entries and exits.
- Spot momentum building in real time
- Catch trend-reversal points before they break
- Built for active traders who need results, not theory

AI Live Economic Dashboard
AI analyzes real-time market data — turning complex, global investment flows into clear insight in seconds.
- Track global stock markets in real time
- See exactly which assets are strong — and which are fading
- Watch how geopolitical events move the markets
About the Author