What the Sharpe Ratio Measures
The Sharpe ratio, developed by Nobel laureate William Sharpe, measures how much excess return an investment generates for each unit of risk (volatility) it takes on. It is calculated as Sharpe Ratio = (Portfolio Return − Risk-Free Rate) ÷ Standard Deviation of Portfolio Returns. A higher Sharpe ratio means an investor is being compensated more generously for the risk taken.

How to Interpret the Numbers
As a general rule of thumb, a Sharpe ratio below 1 is considered subpar, between 1 and 2 is considered good, and above 2 is considered excellent — though acceptable ranges can vary by asset class and time period. Comparing the Sharpe ratios of two strategies with similar returns often reveals that one achieved its performance far more efficiently, with meaningfully less volatility along the way.
Key Limitations
Because the Sharpe ratio treats upside and downside volatility identically, a strategy with large but infrequent positive spikes can be penalized just as much as one with equally large losses, even though investors generally don’t mind upside volatility. This is one reason the Sortino ratio, which counts only downside deviation, is often used alongside the Sharpe ratio for a fuller risk picture.
| Sharpe Ratio | General Interpretation |
|---|---|
| Below 1.0 | Subpar risk-adjusted performance |
| 1.0 – 2.0 | Good risk-adjusted performance |
| Above 2.0 | Excellent risk-adjusted performance |
Frequently Asked Questions
What counts as a ‘good’ Sharpe ratio?
A Sharpe ratio above 1 is generally considered good and above 2 excellent, though the right benchmark depends on the asset class, time period, and the Sharpe ratios of comparable strategies or funds.
Can the Sharpe ratio be negative?
Yes — if a portfolio’s return falls below the risk-free rate, the Sharpe ratio becomes negative, indicating the investment underperformed a virtually risk-free asset while still taking on volatility.
How is the Sharpe ratio different from the Sortino ratio?
The Sharpe ratio uses total volatility (both gains and losses) in its risk measure, while the Sortino ratio uses only downside volatility, making it more forgiving toward strategies with large but favorable price swings.
Does a high Sharpe ratio guarantee future performance?
No — the Sharpe ratio is calculated from historical returns and volatility, so it describes past risk-adjusted performance and offers no guarantee that the same efficiency will continue going forward.
Key Takeaways
The Sharpe ratio measures how much return an investment delivers per unit of risk taken, making it one of the most widely used tools for comparing strategies on a risk-adjusted basis, though it should be viewed alongside other metrics like the Sortino ratio. This article is for informational purposes only and does not constitute investment advice.

QuantPro: AI Finds the Trade Before You Do
From AI-powered chart analysis to real-time market intelligence — everything a serious investor needs, in one platform.
- Automated AI chart analysis with precision trend timing
- Bull Radar: real-time visualization of geopolitical & economic shifts
- Live market-moving news and insights, curated for you
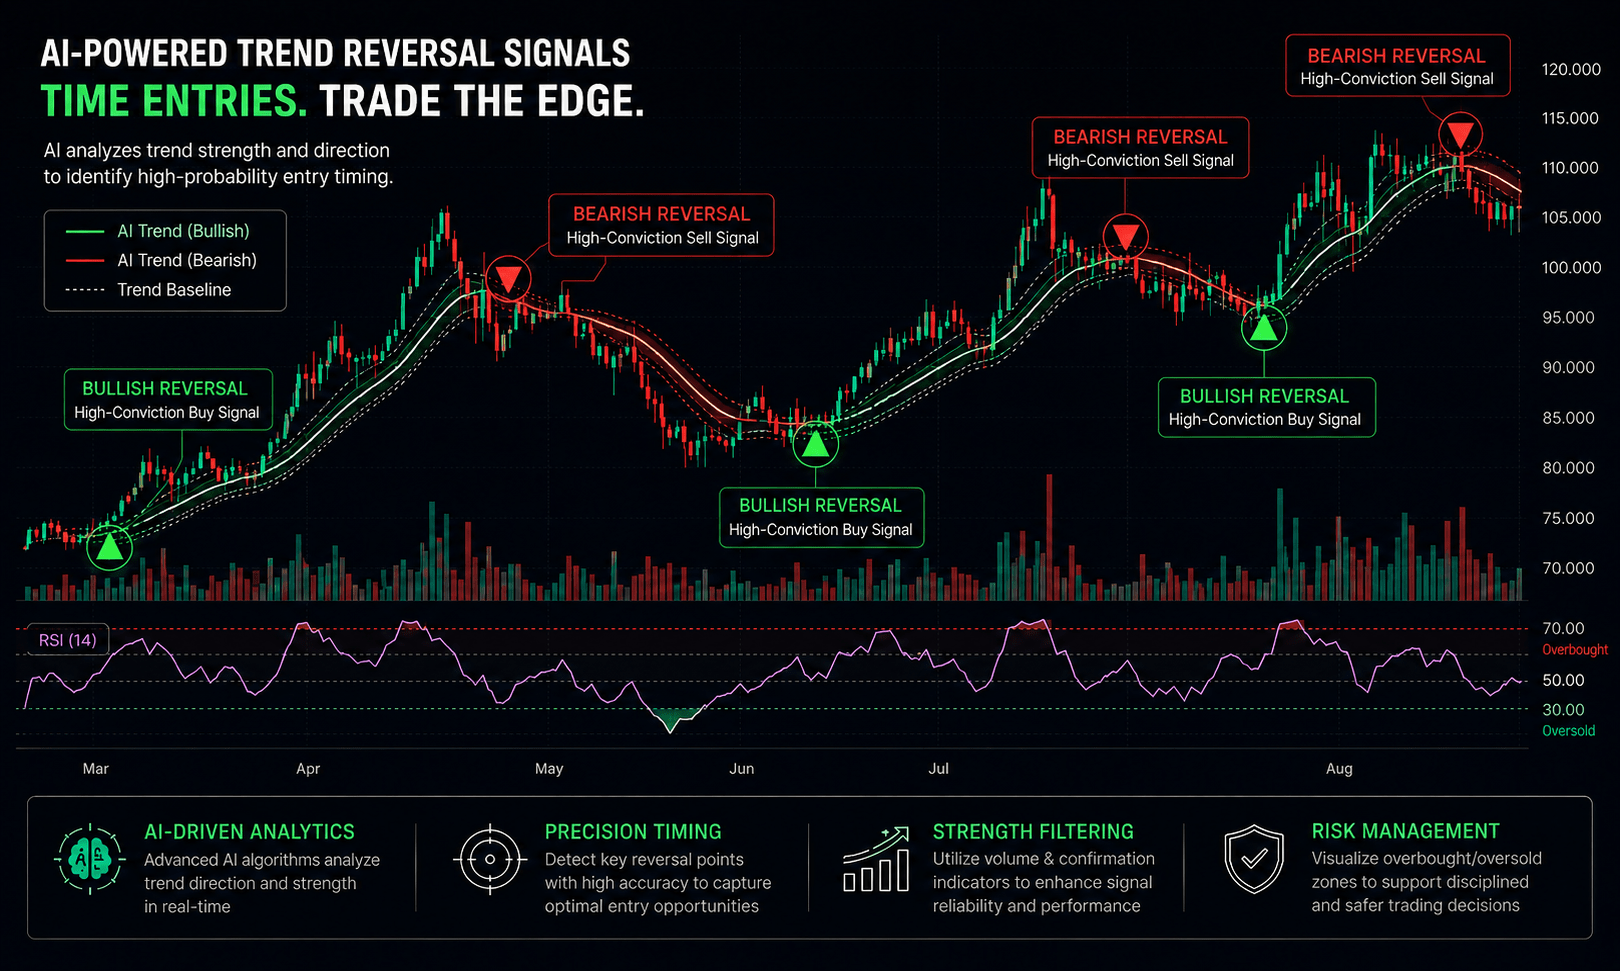
Bull Wave / Bear Wave Forecast Model
Engineered to help you read market direction and momentum faster than the crowd.
- Instantly separate bullish momentum from bearish pressure
- Pinpoint high-probability entry zones with confidence
- Chart signals clear enough for beginners, sharp enough for pros
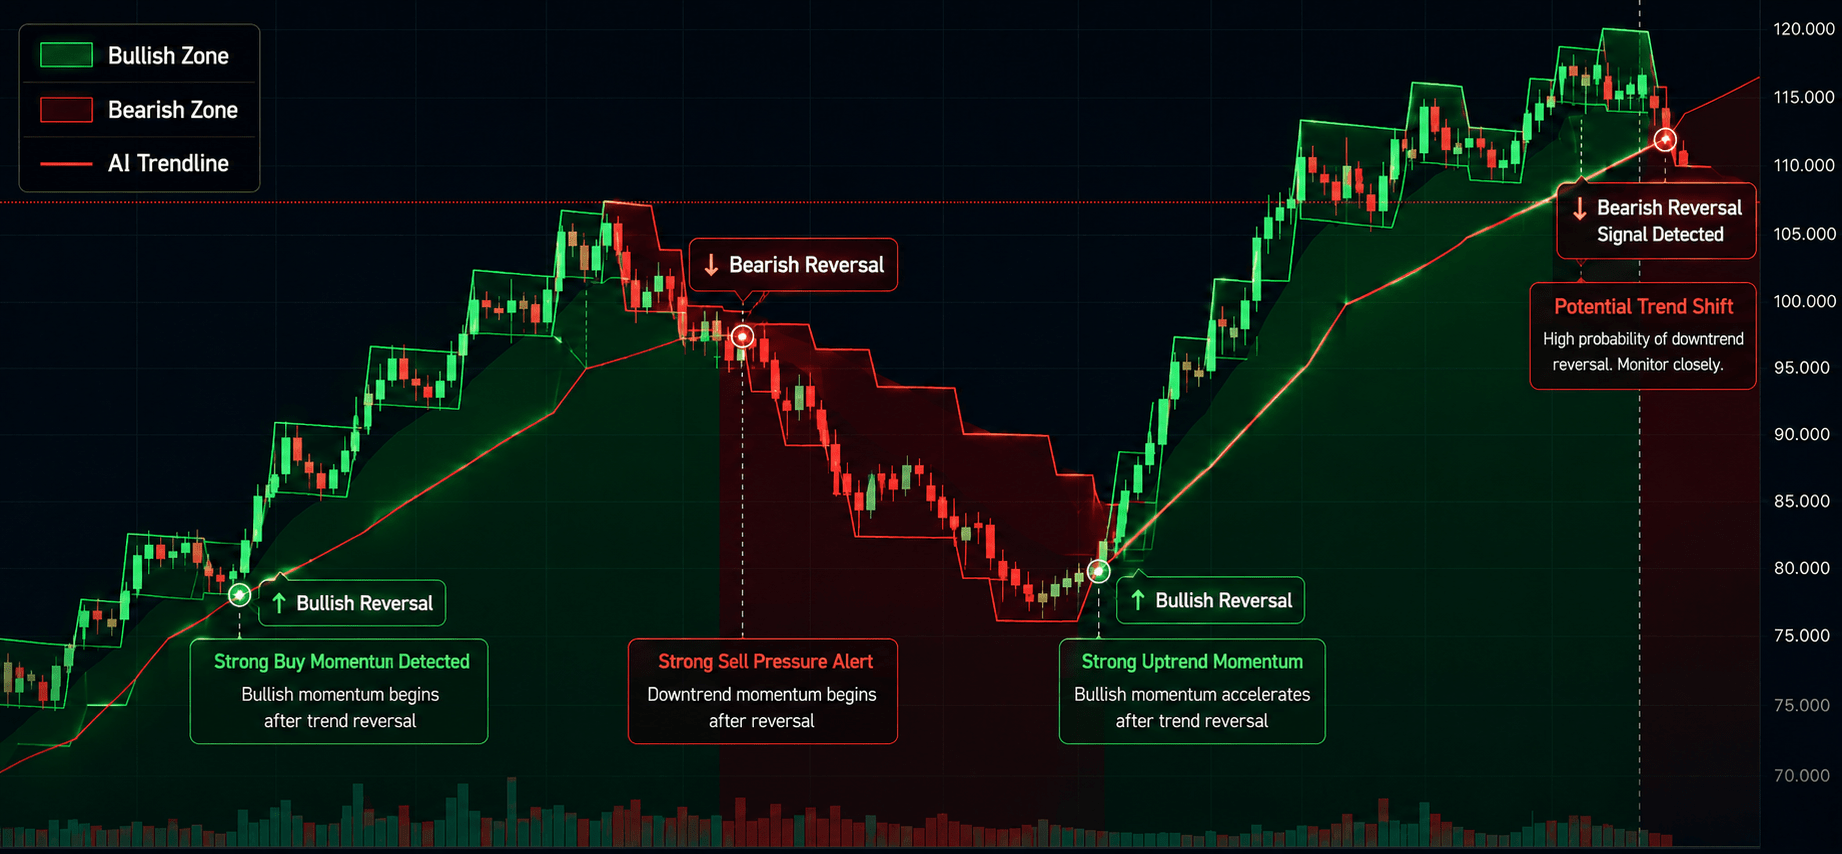
Winning Pattern Detection
Instantly surfaces the high-probability setups that repeat across the charts — a trusted edge for timing your entries and exits.
- Spot momentum building in real time
- Catch trend-reversal points before they break
- Built for active traders who need results, not theory
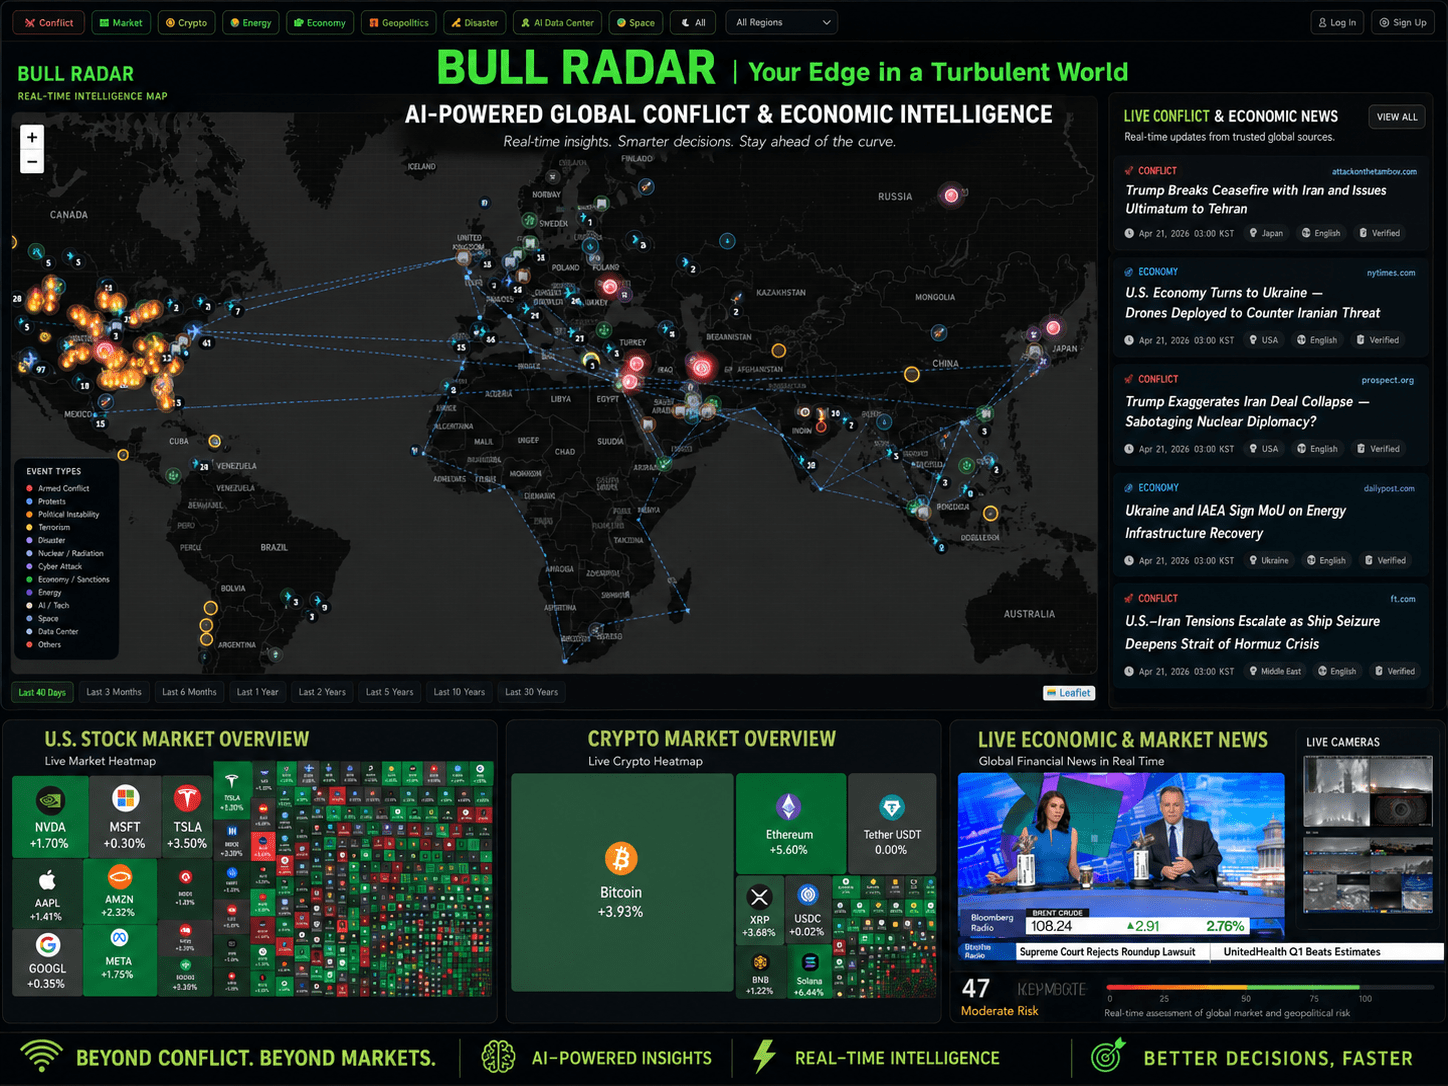
AI Live Economic Dashboard
AI analyzes real-time market data — turning complex, global investment flows into clear insight in seconds.
- Track global stock markets in real time
- See exactly which assets are strong — and which are fading
- Watch how geopolitical events move the markets
About the Author