Definition
The Graham Number is a formula developed by Benjamin Graham, the father of value investing, to estimate the maximum price a defensive investor should reasonably pay for a stock. It combines a company’s earnings and book value into a single conservative fair-value ceiling, reflecting Graham’s belief that a stock’s price should be justified by both its earning power and the hard assets standing behind it.
How It’s Calculated
The formula is: Graham Number = square root of (22.5 x EPS x Book Value per Share). The constant 22.5 comes from multiplying Graham’s two rule-of-thumb ceilings: a maximum price-to-earnings ratio of 15 and a maximum price-to-book ratio of 1.5 (15 x 1.5 = 22.5). Suppose a company reports EPS of $3.20 and Book Value per Share of $28.00. Its Graham Number is the square root of (22.5 x 3.20 x 28.00) = the square root of 2,016 = approximately $44.90.
Worked Example: Comparing to the Market Price
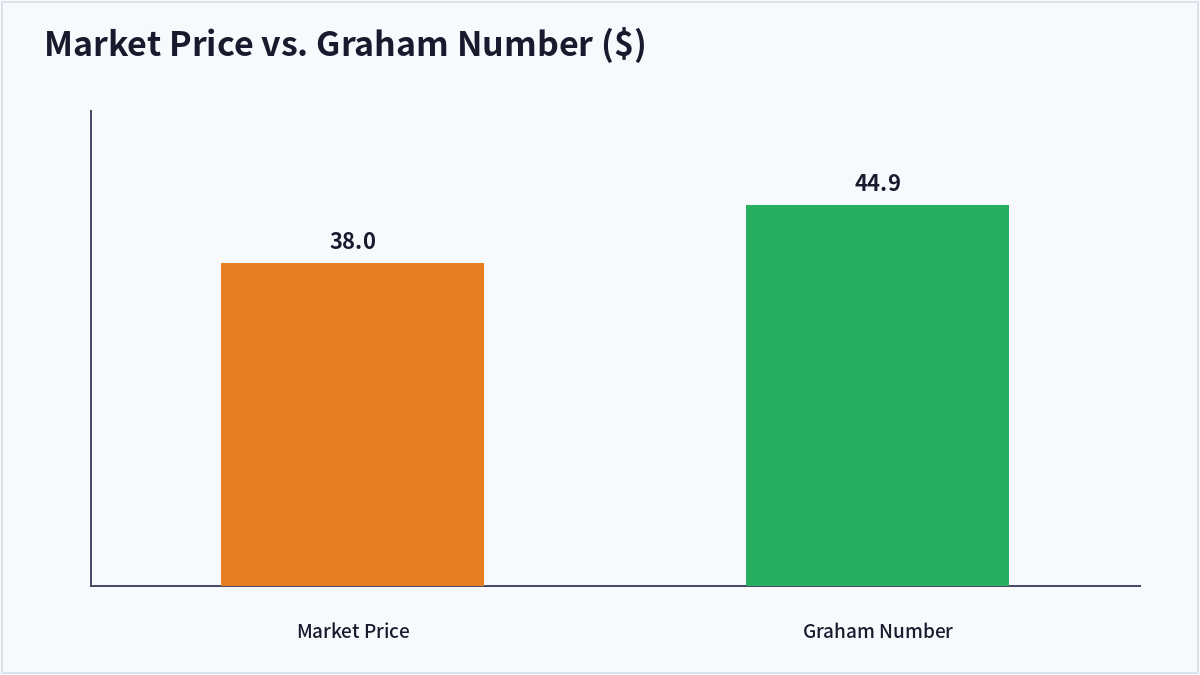
If that same stock is currently trading at $38.00, it sits below its $44.90 Graham Number, implying a margin of safety of about (44.90 – 38.00) / 44.90 = 15.4%. Graham considered this gap the buffer that protects an investor against estimation errors, unforeseen bad news, or a market downturn.
Why It Matters: Margin-of-Safety Logic
Graham’s central investing principle was to buy securities for meaningfully less than a conservative estimate of their intrinsic value, so that even if the estimate proves optimistic, the investor is protected from serious loss. The Graham Number operationalizes this by capping both the earnings multiple and the book value multiple an investor should accept, rather than relying on optimistic growth assumptions. It works best for stable, profitable, asset-heavy businesses — the kind of mature, defensive companies Graham favored — and is far less meaningful for early-stage, asset-light, or currently unprofitable companies.
Comparison: Graham Number vs. Other Valuation Methods
| Method | What It Uses | Main Limitation |
|---|---|---|
| Graham Number | EPS and Book Value per Share | Unreliable for negative earnings or book value |
| P/E Ratio | Price relative to earnings only | Ignores balance sheet strength |
| Discounted Cash Flow (DCF) | Projected future free cash flows | Highly sensitive to growth and discount rate assumptions |
Frequently Asked Questions
What does the constant 22.5 represent?
It represents the product of Graham’s two acceptable valuation ceilings for a defensive investor: a maximum P/E of 15 and a maximum P/B of 1.5. Multiplying 15 by 1.5 gives 22.5, which is why it appears inside the square root in the formula.
Can the Graham Number be used for all stocks?
No. It works best for established, profitable companies with meaningful tangible book value, such as industrials, financials, and mature consumer businesses. It tends to understate fair value for asset-light, high-growth companies like software firms, whose value lies mostly in future cash flows rather than current book assets.
How is the Graham Number different from intrinsic value from a DCF model?
The Graham Number is a quick, backward-looking screen based only on current EPS and book value, while a DCF model estimates intrinsic value from projected future cash flows discounted back to the present. The Graham Number is far simpler and more conservative but ignores growth entirely, whereas a DCF can capture growth but is much more sensitive to the assumptions used.
What if EPS or book value is negative?
The formula becomes meaningless if either input is negative, since the number under the square root would be negative and produce no real result. Graham never intended the formula for unprofitable companies or those with negative equity, which is itself a signal that his framework does not apply to that stock.
Key Takeaways
The Graham Number, calculated as the square root of 22.5 times EPS times Book Value per Share, gives a conservative estimate of the maximum price a defensive value investor should pay for a stock. It embodies Benjamin Graham’s margin-of-safety philosophy by capping both the earnings and book-value multiples used in the calculation, but it is best applied to stable, profitable, asset-backed companies rather than growth or loss-making businesses. This article is for informational purposes only and does not constitute investment advice.

QuantPro: AI Finds the Trade Before You Do
From AI-powered chart analysis to real-time market intelligence — everything a serious investor needs, in one platform.
- Automated AI chart analysis with precision trend timing
- Bull Radar: real-time visualization of geopolitical & economic shifts
- Live market-moving news and insights, curated for you
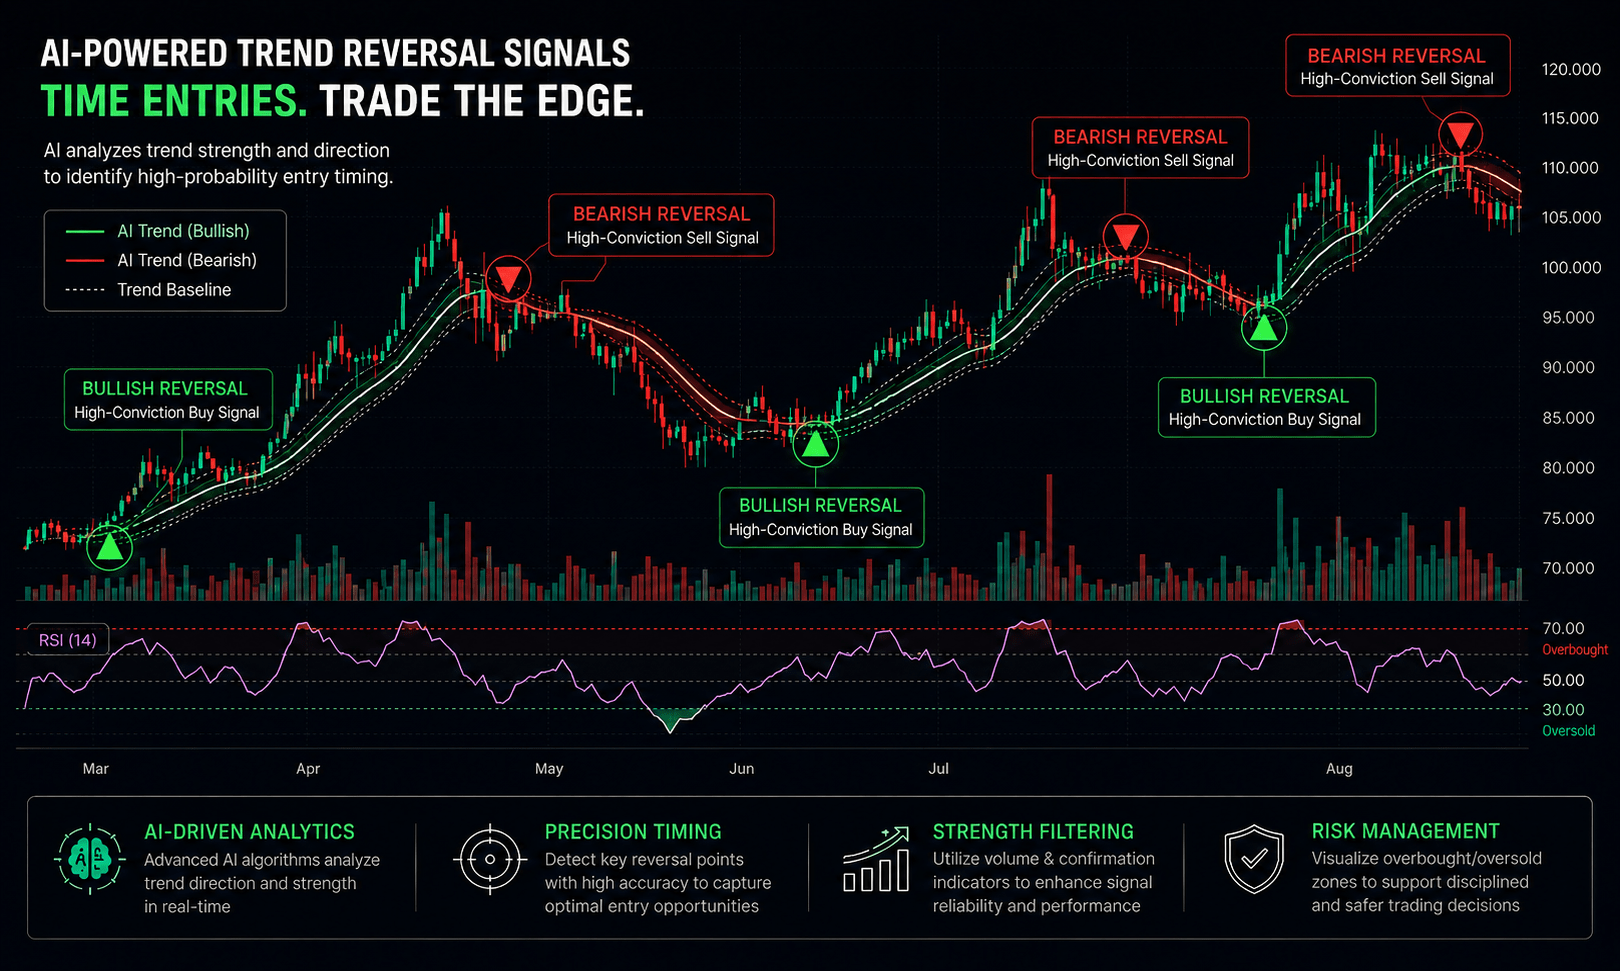
Bull Wave / Bear Wave Forecast Model
Engineered to help you read market direction and momentum faster than the crowd.
- Instantly separate bullish momentum from bearish pressure
- Pinpoint high-probability entry zones with confidence
- Chart signals clear enough for beginners, sharp enough for pros
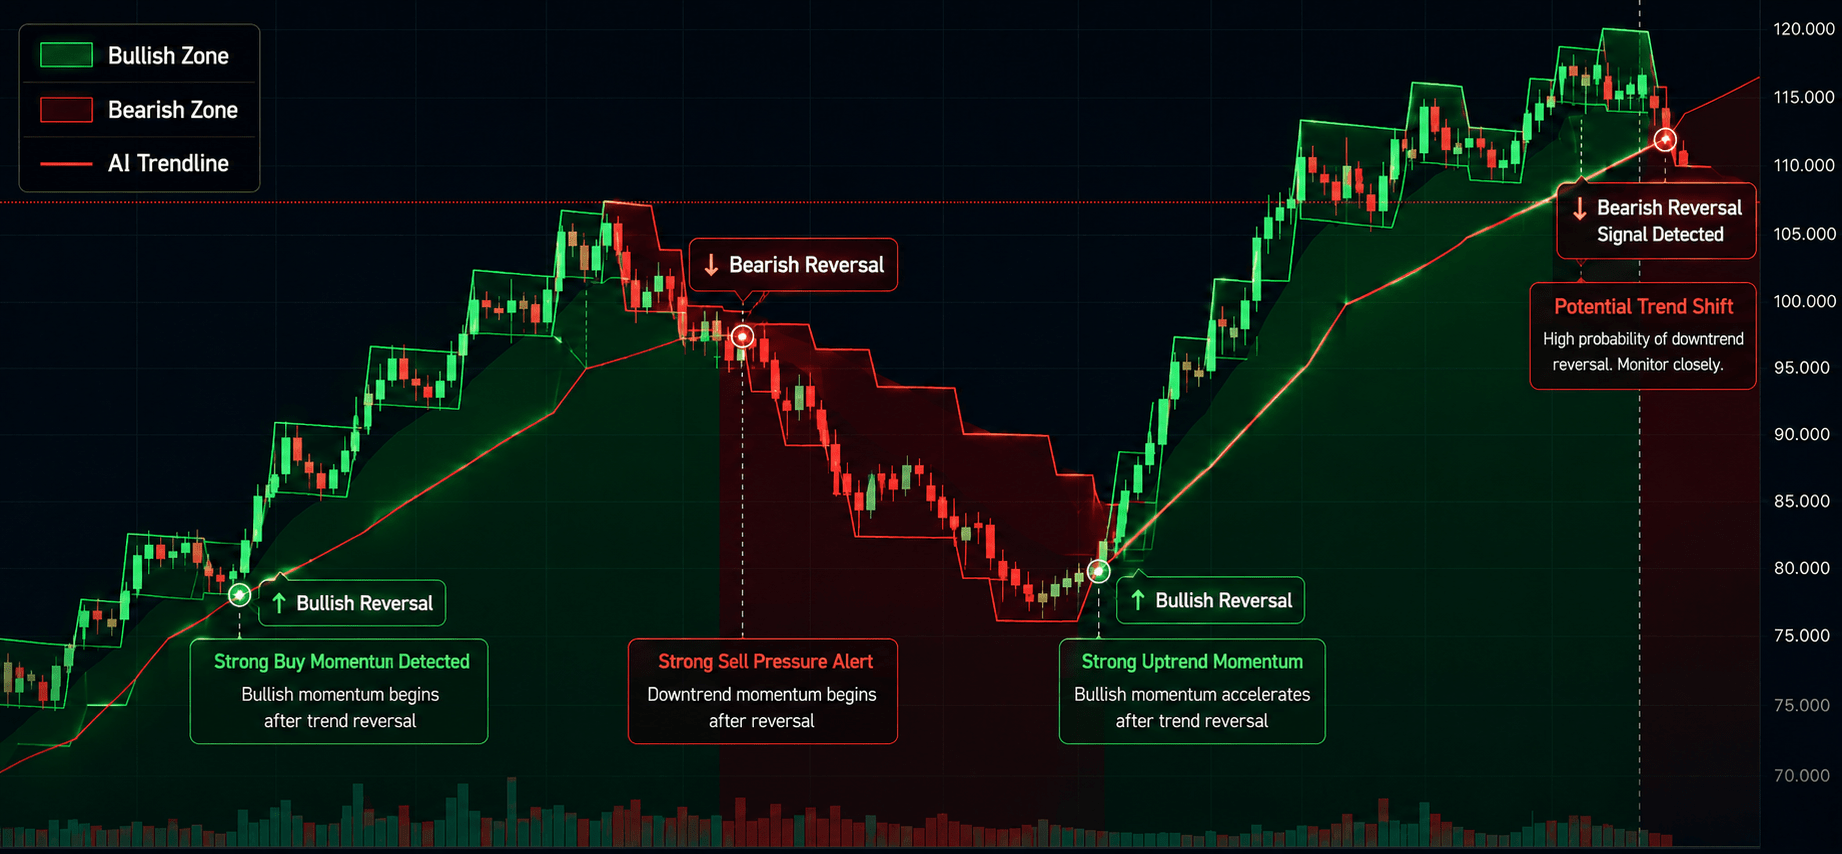
Winning Pattern Detection
Instantly surfaces the high-probability setups that repeat across the charts — a trusted edge for timing your entries and exits.
- Spot momentum building in real time
- Catch trend-reversal points before they break
- Built for active traders who need results, not theory
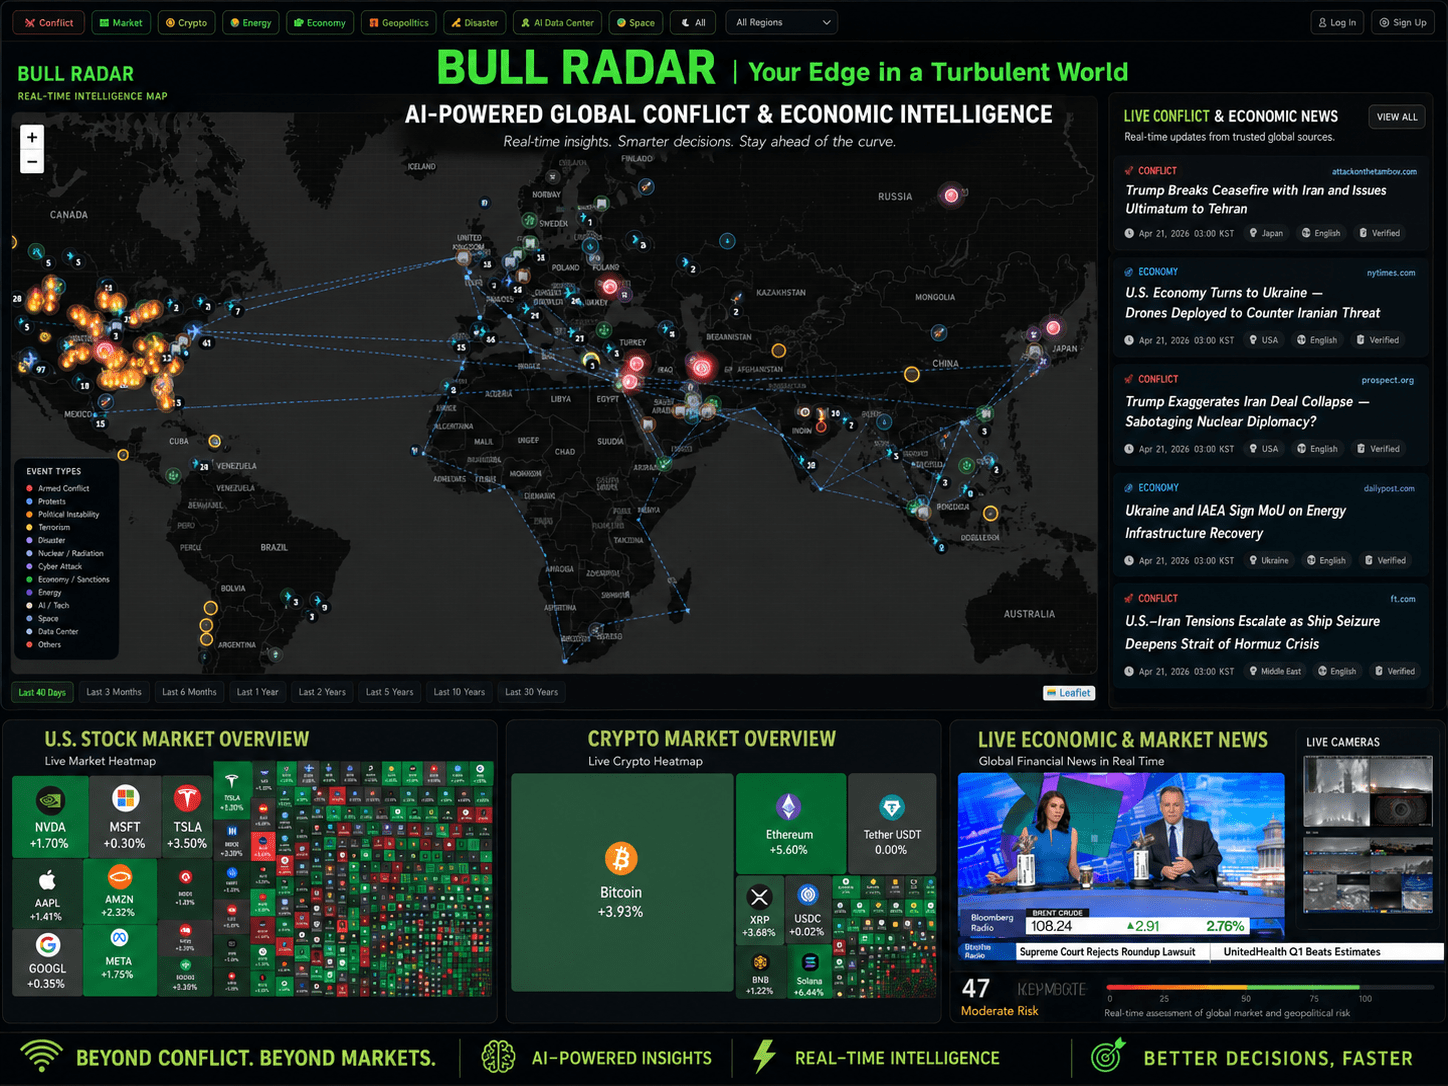
AI Live Economic Dashboard
AI analyzes real-time market data — turning complex, global investment flows into clear insight in seconds.
- Track global stock markets in real time
- See exactly which assets are strong — and which are fading
- Watch how geopolitical events move the markets
About the Author