What Put-Call Parity States
Put-call parity is a pricing relationship that must hold between a call and a put option sharing the same underlying asset, strike price, and expiration date. The formula reads: call price minus put price equals the underlying’s current price minus the present value of the strike price.
Why the Relationship Holds
A portfolio that buys a call and sells a put at the same strike produces the exact same payoff structure at expiration as simply holding the underlying asset outright. Because both portfolios deliver identical payoffs, their present values must be equal, or an arbitrage opportunity exists.
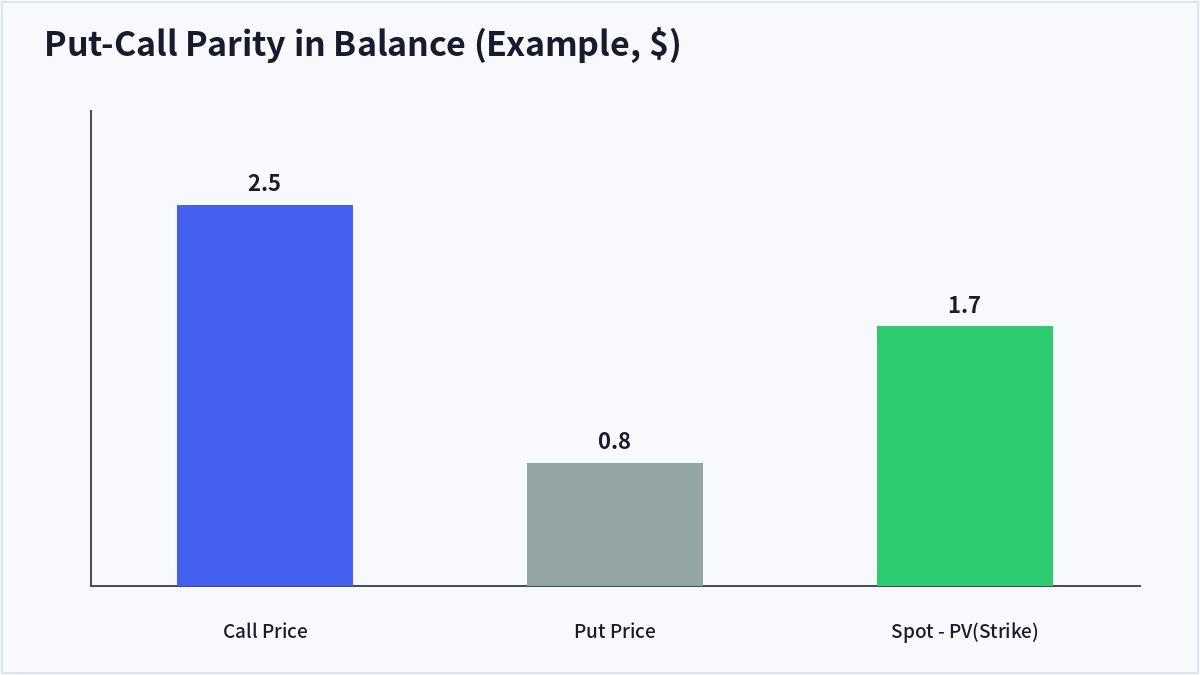
Arbitrage When Parity Breaks
If a call trades above its parity-implied price, a trader can sell the call, buy the put, and buy the underlying to lock in a theoretically riskless profit. In practice, well-monitored liquid markets close such gaps almost immediately as arbitrageurs step in.
Adjusting for Dividends
When the underlying is a dividend-paying stock, the formula must be adjusted for the present value of expected dividends to remain accurate, which is why call and put prices often shift relative to each other around ex-dividend dates.
| Component | Role |
|---|---|
| Long Call | Gains if underlying rises |
| Short Put | Loses if underlying falls |
| Combined Position | Replicates holding the underlying outright |
Frequently Asked Questions
Does put-call parity apply to all options?
It holds precisely for European-style options, which can only be exercised at expiration; American-style options, which allow early exercise, can deviate slightly from strict parity.
How often do real arbitrage opportunities appear?
In liquid markets, institutional players monitor pricing gaps continuously, so any parity violation tends to be corrected within a very short window.
Why should retail investors understand this concept?
Even without executing arbitrage trades directly, understanding that call and put prices are mathematically linked helps investors judge whether an option’s price looks reasonable relative to its counterpart.
What is a synthetic position?
By combining calls, puts, and the underlying asset according to put-call parity, traders can construct a synthetic position that replicates the payoff of a different instrument entirely.
Key Takeaways
Put-call parity defines the equilibrium relationship between call prices, put prices, and the underlying asset, and any break from that balance creates a theoretical arbitrage opportunity. It’s a foundational concept for understanding how options prices are interconnected. This article is for informational purposes only and does not constitute investment advice.

QuantPro: AI Finds the Trade Before You Do
From AI-powered chart analysis to real-time market intelligence — everything a serious investor needs, in one platform.
- Automated AI chart analysis with precision trend timing
- Bull Radar: real-time visualization of geopolitical & economic shifts
- Live market-moving news and insights, curated for you
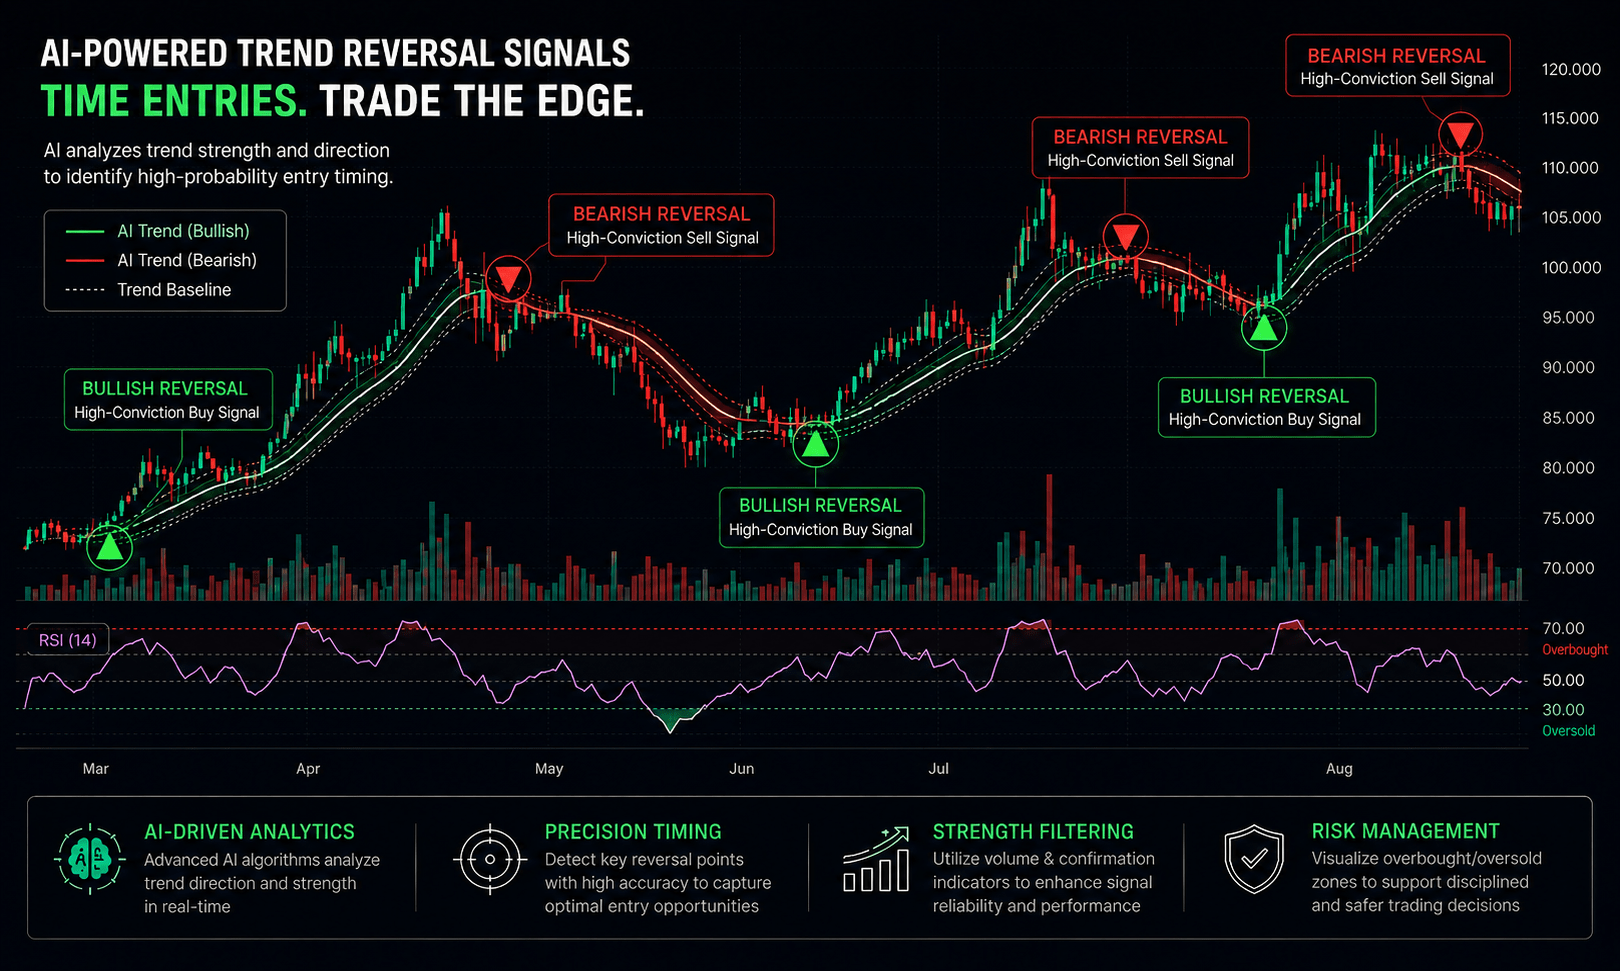
Bull Wave / Bear Wave Forecast Model
Engineered to help you read market direction and momentum faster than the crowd.
- Instantly separate bullish momentum from bearish pressure
- Pinpoint high-probability entry zones with confidence
- Chart signals clear enough for beginners, sharp enough for pros
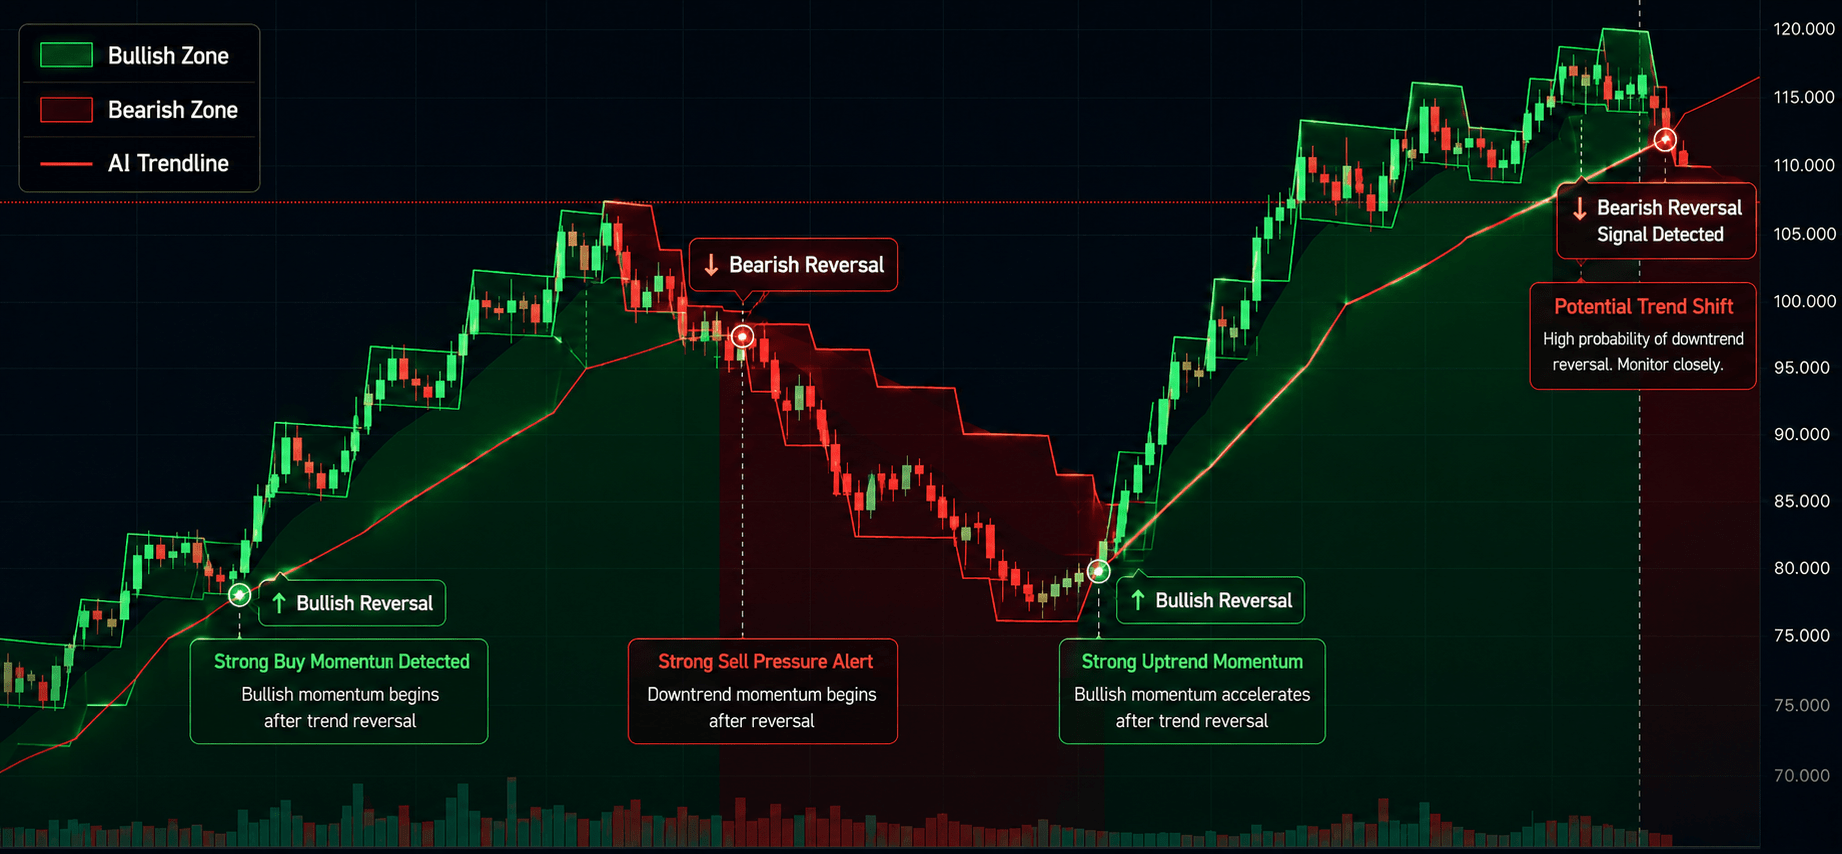
Winning Pattern Detection
Instantly surfaces the high-probability setups that repeat across the charts — a trusted edge for timing your entries and exits.
- Spot momentum building in real time
- Catch trend-reversal points before they break
- Built for active traders who need results, not theory
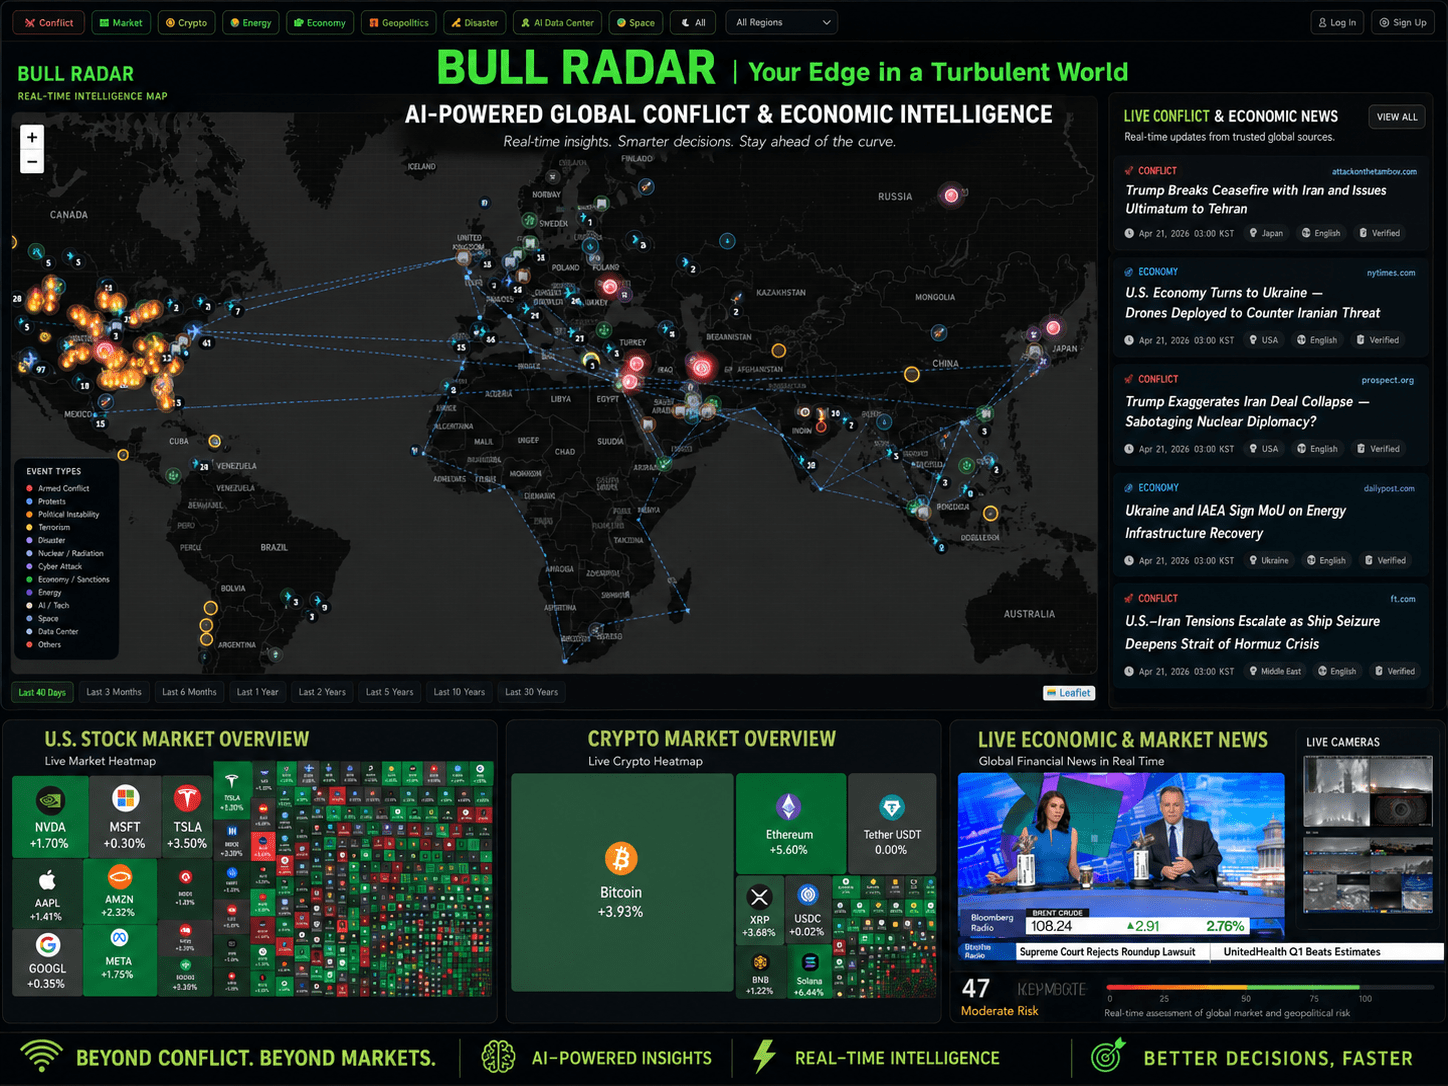
AI Live Economic Dashboard
AI analyzes real-time market data — turning complex, global investment flows into clear insight in seconds.
- Track global stock markets in real time
- See exactly which assets are strong — and which are fading
- Watch how geopolitical events move the markets
About the Author