Defining a Credit Default Swap
A credit default swap (CDS) is a derivative contract that transfers the default risk of a bond or entity (the reference asset) from one party to another. The buyer of protection pays a periodic insurance-like premium (the spread), and if a defined credit event — such as default — occurs, the seller compensates the buyer for the resulting loss.
How the Trade Is Structured
A bondholder (the protection buyer) pays an annual fee, quoted in basis points on the bond’s notional value, to a bank or hedge fund (the protection seller). If a default occurs, the seller pays the buyer the difference between the bond’s face value and its recovery value.
| Party | Role |
|---|---|
| Protection Buyer | Pays premium, receives payout on default |
| Protection Seller | Collects premium, pays out on default |
| Reference Entity | The bond, company, or country the CDS covers |
Why the Spread Reflects Credit Risk
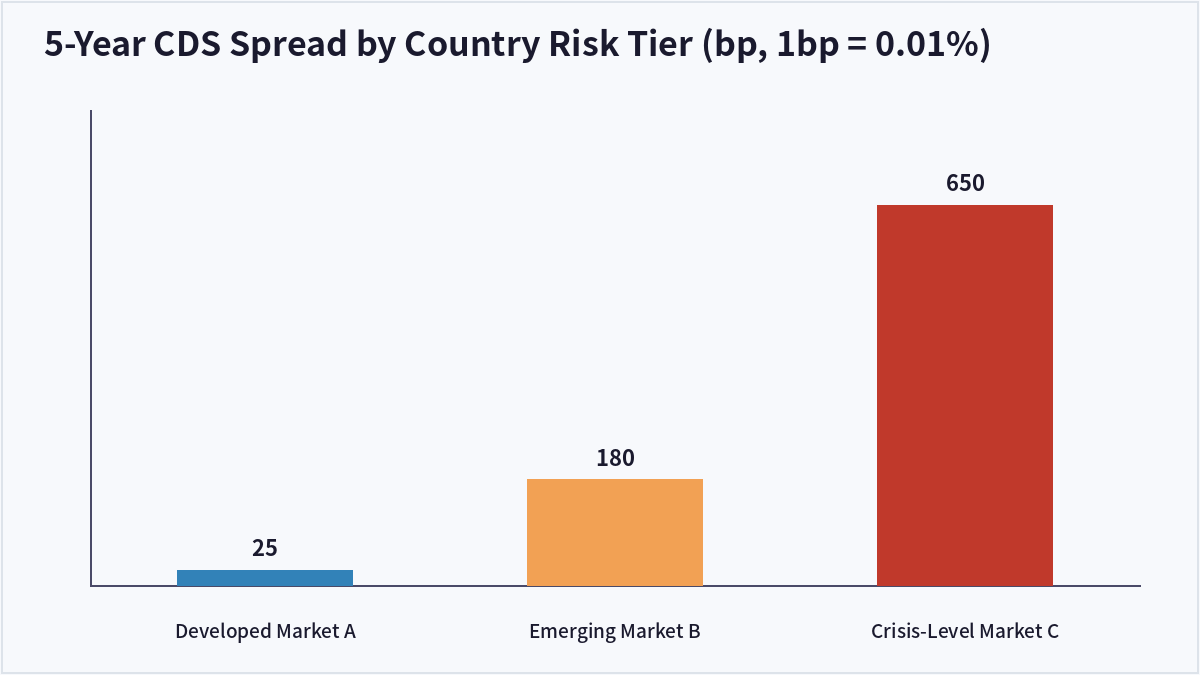
The more likely the market believes a default is, the higher premium a protection seller will demand — so the CDS spread itself functions as a real-time, market-based gauge of perceived credit risk. Sovereign CDS spreads are widely used as an indicator of a country’s perceived default risk on its government debt.
The 2008 Financial Crisis and CDS
During the 2008 financial crisis, large insurers like AIG had sold massive volumes of CDS protection tied to subprime mortgage debt, and when defaults cascaded, they faced enormous payout obligations — an episode that exposed the systemic risk embedded in the CDS market to the world.
How Investors Use CDS Spreads
Even investors who never trade CDS directly can treat a sharp widening in a company’s or country’s CDS spread as a signal that the market is reassessing credit risk, useful context for related bond or equity decisions.
Frequently Asked Questions
Do you need to own the underlying bond to trade a CDS?
No — “naked” CDS positions, taken without owning the reference bond, are common and allow purely speculative bets on credit risk, a practice that has drawn regulatory scrutiny.
What units are CDS spreads quoted in?
CDS spreads are typically quoted in basis points (bp), where 1 bp equals 0.01 percentage points — a spread of 100 bp means paying 1% of notional annually.
Do credit ratings and CDS spreads always move together?
Not always in timing — because CDS spreads trade continuously in the market while credit ratings are reviewed periodically by rating agencies, spread movements often signal changing risk perceptions before a formal rating change occurs.
Can individual investors trade CDS directly?
CDS contracts trade mostly in the institutional over-the-counter market, making direct access difficult for individual investors, who instead tend to monitor CDS spread data as a reference indicator.
Key Takeaways
A credit default swap transfers bond default risk between parties for a periodic premium, and its spread serves as a widely watched, real-time market gauge of perceived credit risk. This article is for informational purposes only and does not constitute investment advice.

QuantPro: AI Finds the Trade Before You Do
From AI-powered chart analysis to real-time market intelligence — everything a serious investor needs, in one platform.
- Automated AI chart analysis with precision trend timing
- Bull Radar: real-time visualization of geopolitical & economic shifts
- Live market-moving news and insights, curated for you
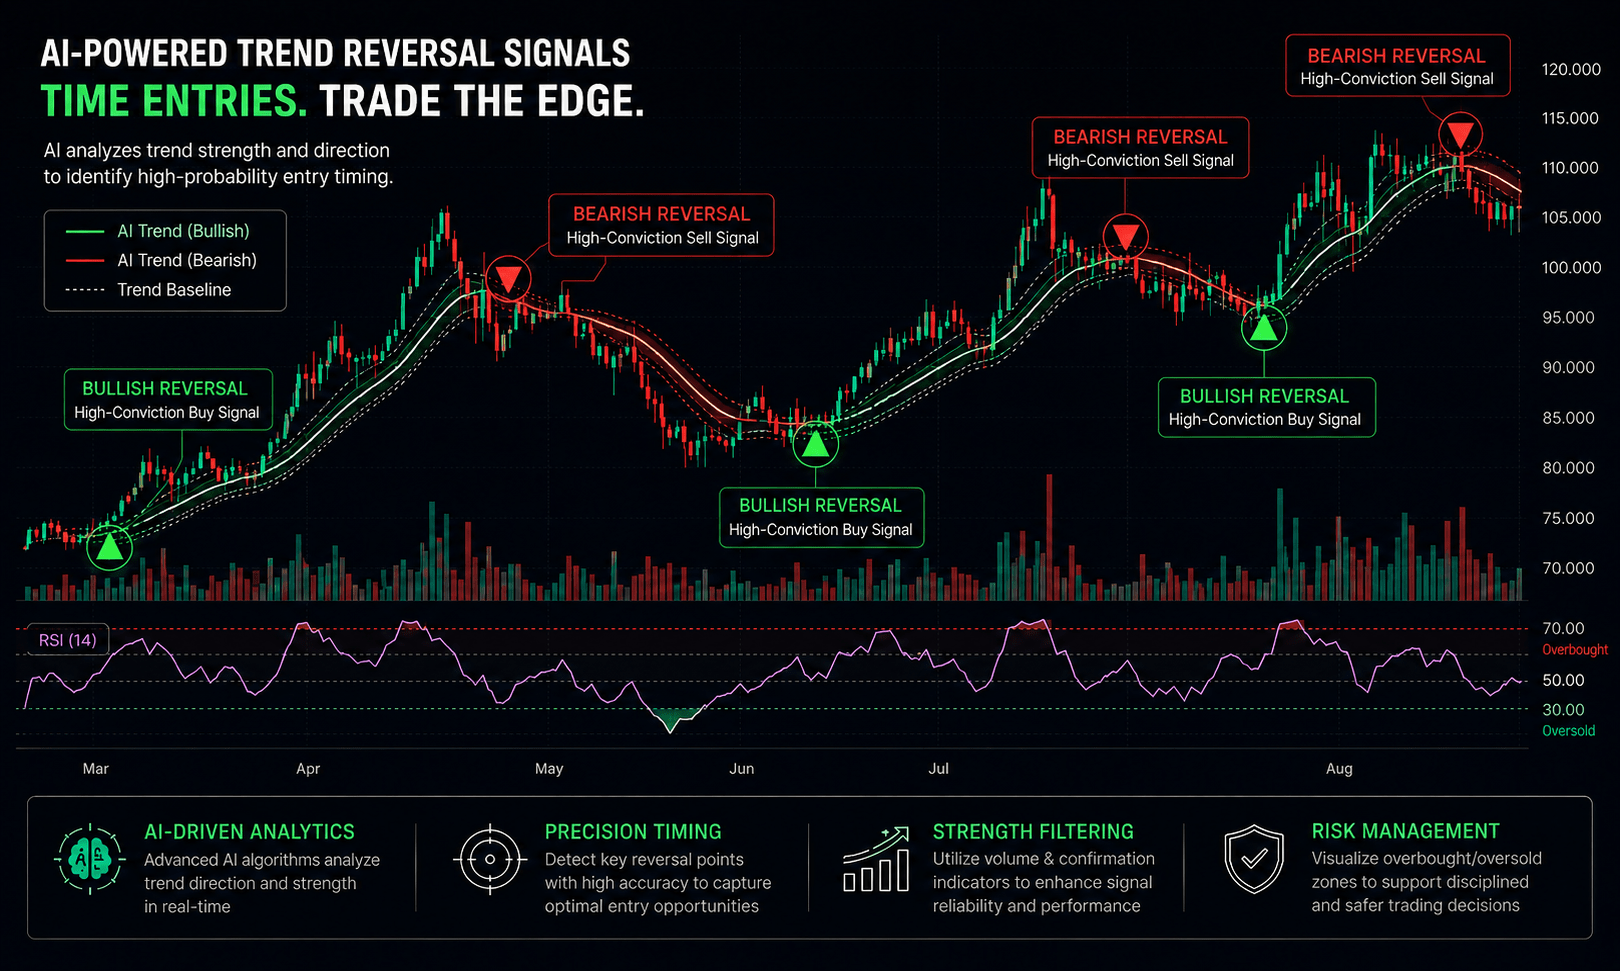
Bull Wave / Bear Wave Forecast Model
Engineered to help you read market direction and momentum faster than the crowd.
- Instantly separate bullish momentum from bearish pressure
- Pinpoint high-probability entry zones with confidence
- Chart signals clear enough for beginners, sharp enough for pros
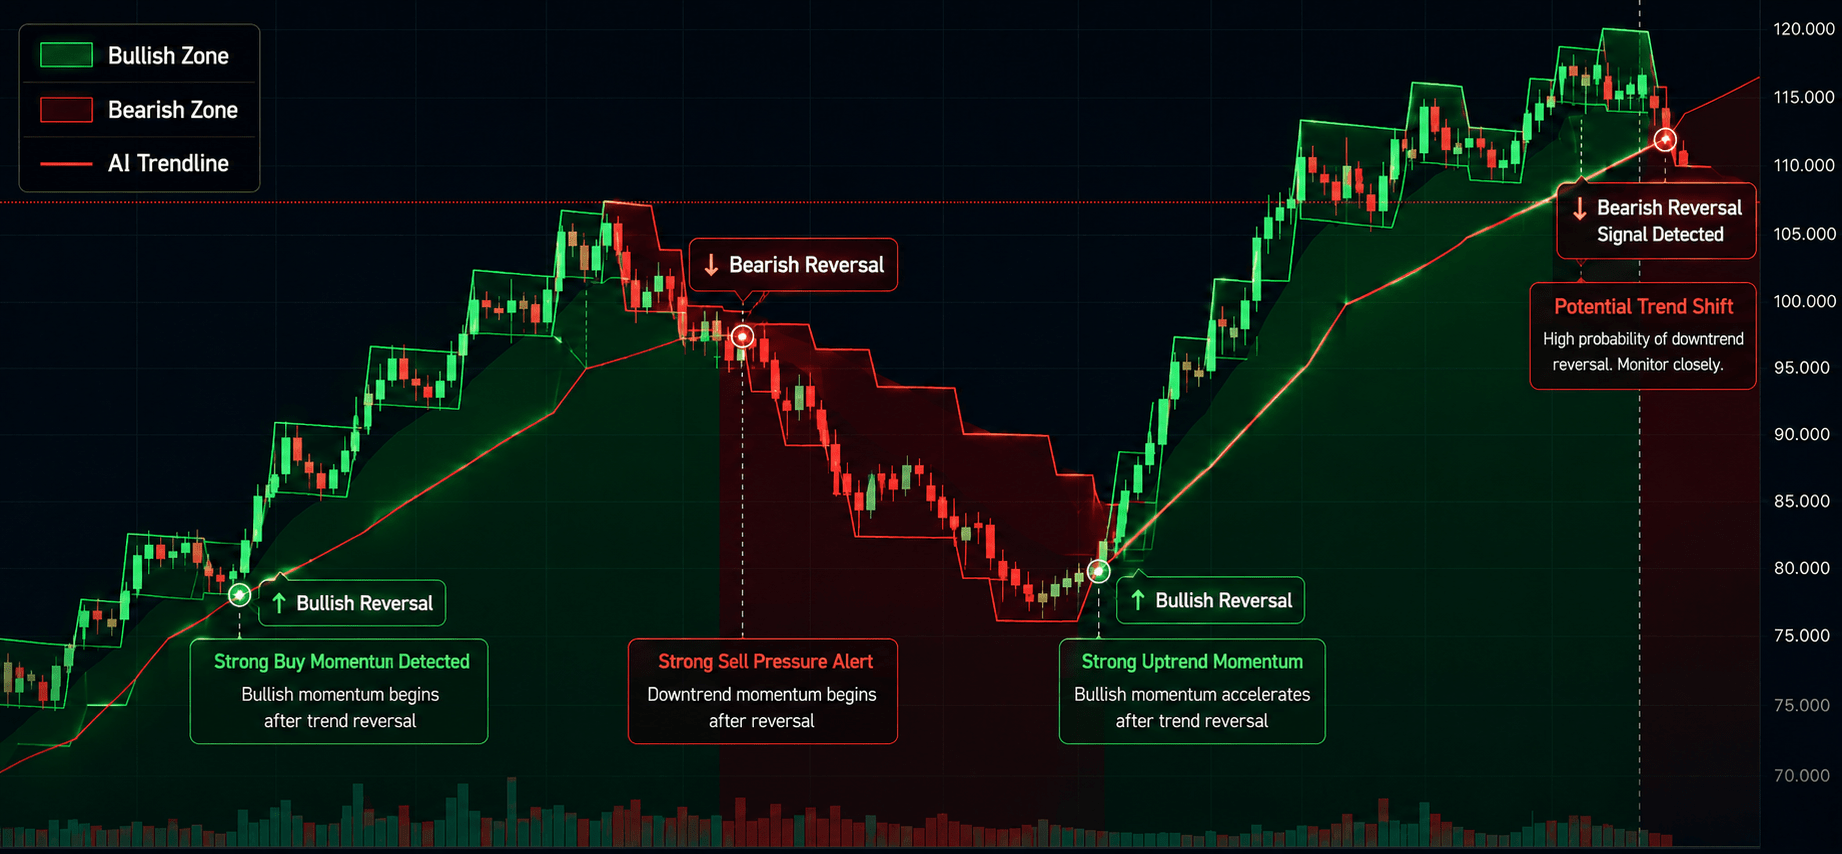
Winning Pattern Detection
Instantly surfaces the high-probability setups that repeat across the charts — a trusted edge for timing your entries and exits.
- Spot momentum building in real time
- Catch trend-reversal points before they break
- Built for active traders who need results, not theory
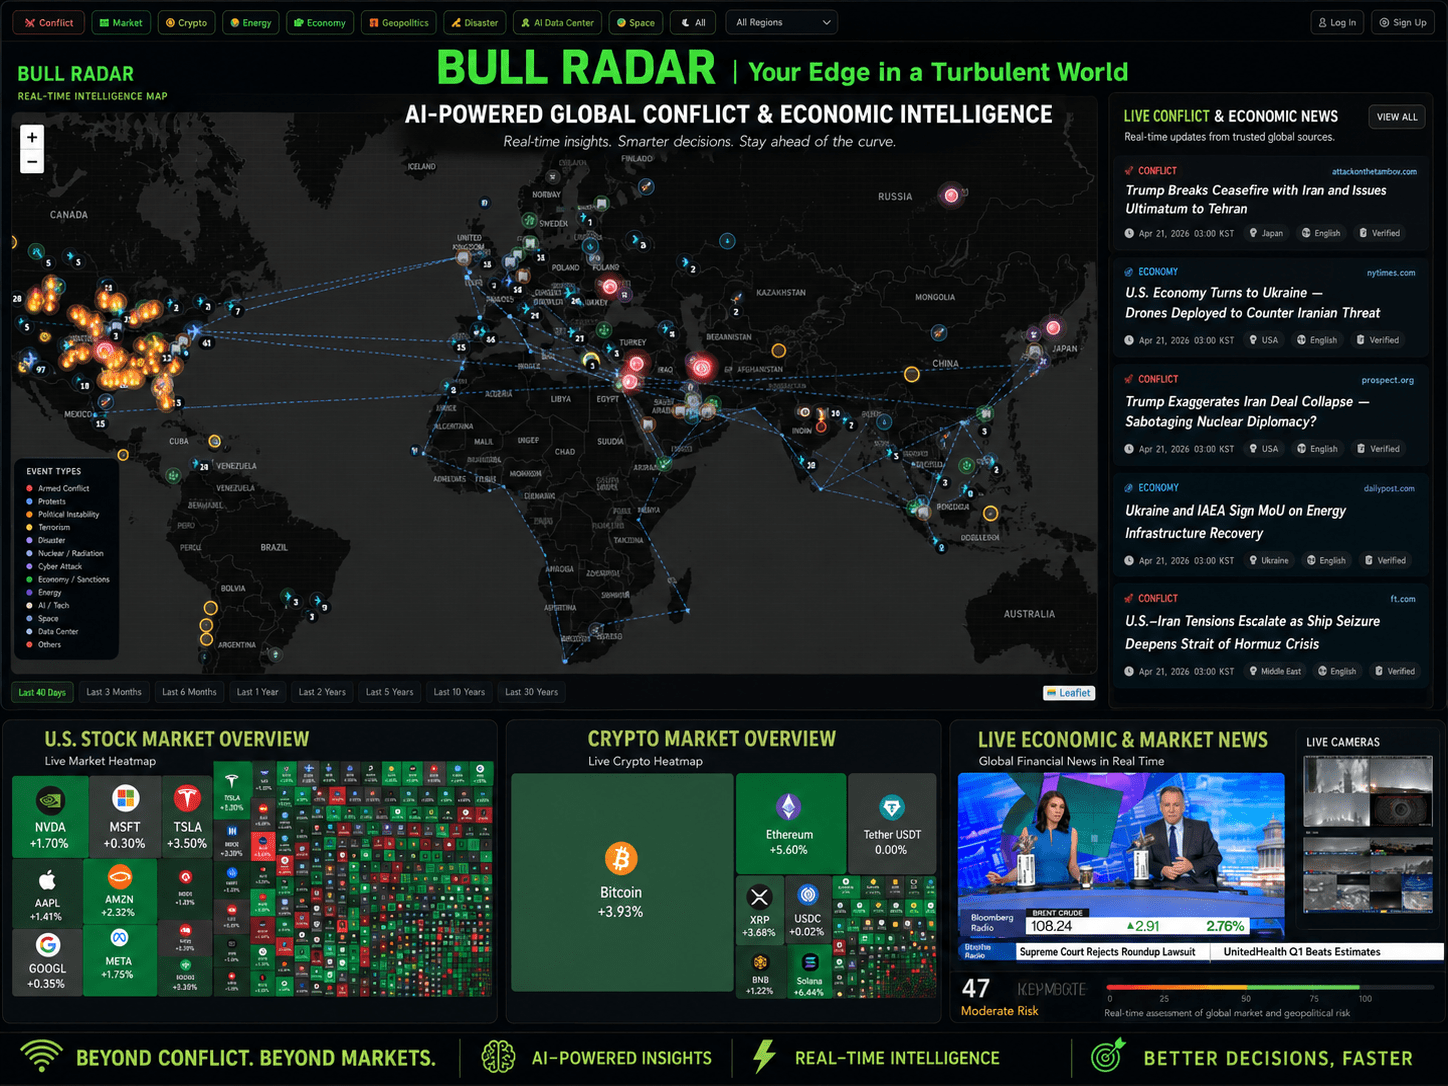
AI Live Economic Dashboard
AI analyzes real-time market data — turning complex, global investment flows into clear insight in seconds.
- Track global stock markets in real time
- See exactly which assets are strong — and which are fading
- Watch how geopolitical events move the markets
About the Author