What Duration Measures
Duration estimates the approximate percentage change in a bond’s price for a 1 percentage point change in interest rates, making it the most basic tool for measuring a bond’s interest rate sensitivity. A duration of 5 years implies roughly a 5% price decline for each 1-point rise in rates.
Duration Is a Linear Approximation
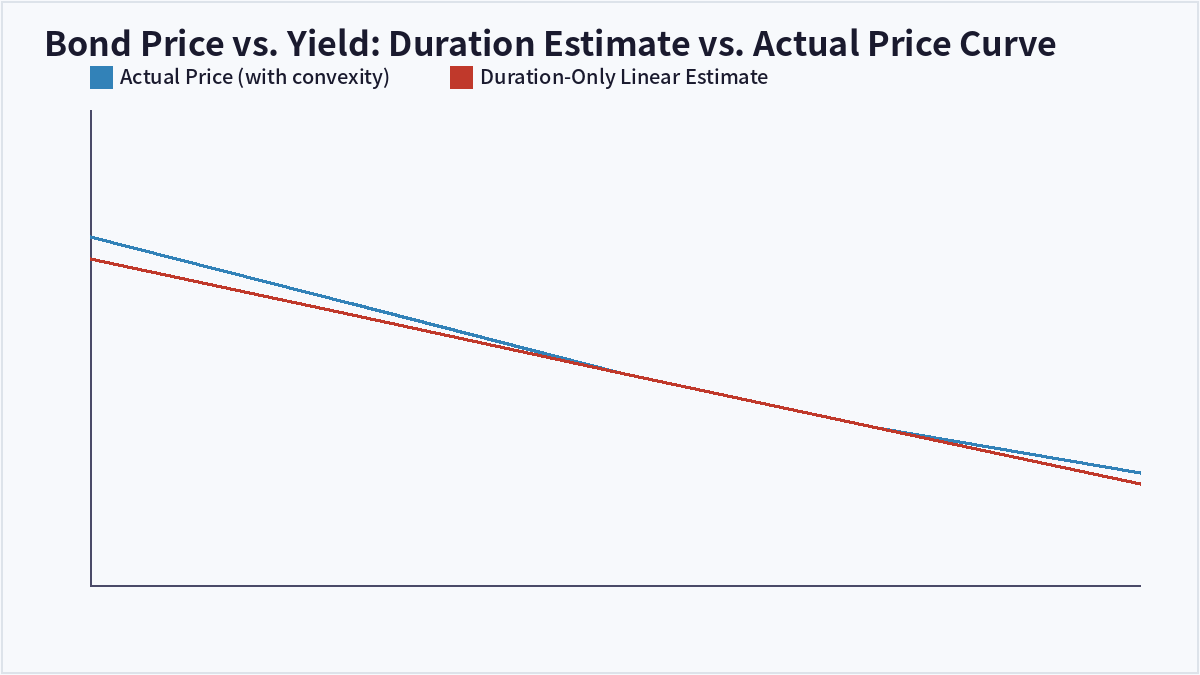
Using duration to estimate price changes assumes a straight-line (linear) relationship between yield and price. In reality, the relationship between bond prices and yields is convex — it curves — so duration’s linear estimate is accurate for small rate moves but increasingly diverges from the true price as the move gets larger.
| Metric | What It Measures | Best For |
|---|---|---|
| Duration | Slope of the price-yield relationship (1st-order) | Small rate changes |
| Convexity | Curvature of the price-yield relationship (2nd-order) | Correcting for larger rate changes |
Why Convexity Matters
Convexity measures how curved the price-yield relationship is. For a standard bond with positive convexity, prices rise more than duration alone predicts when rates fall, and fall less than duration predicts when rates rise — an asymmetry that works in the bondholder’s favor.
Putting Numbers to It
A more precise price-change formula is: % price change ≈ -Duration × Δyield + 0.5 × Convexity × (Δyield)². When rates move by just 0.1 percentage points, the convexity term is nearly negligible, but when rates swing by 2 points or more, that second term becomes material to the actual outcome.
The Role of Maturity and Coupon
In general, bonds with longer maturities and lower coupon rates have both higher duration and higher convexity. This is why long-dated Treasuries or zero-coupon bonds are far more sensitive to interest rate changes than short-term corporate bonds with higher coupons.
Frequently Asked Questions
Is convexity always positive?
Most plain-vanilla coupon bonds have positive convexity, but structures with embedded call options — callable bonds — can exhibit negative convexity because falling rates increase the risk of early redemption.
If two bonds have the same duration, do they behave identically?
Not necessarily — if their convexity differs, their price behavior can diverge meaningfully during large rate moves, so a full comparison should consider both metrics.
How is this used in portfolio management?
When rate volatility is expected to rise, managers often prefer bonds with higher convexity at a given duration, since that structure benefits more on rallies and loses less on selloffs.
What’s the difference between modified and Macaulay duration?
Macaulay duration measures the weighted-average time (in years) to receive a bond’s cash flows, while modified duration adapts this measure to directly approximate the percentage price change for a given yield change.
Key Takeaways
Duration provides a linear first-order estimate of a bond’s rate sensitivity, while convexity corrects that estimate for the curve’s true shape, and both matter more as rate volatility increases. This article is for informational purposes only and does not constitute investment advice.

QuantPro: AI Finds the Trade Before You Do
From AI-powered chart analysis to real-time market intelligence — everything a serious investor needs, in one platform.
- Automated AI chart analysis with precision trend timing
- Bull Radar: real-time visualization of geopolitical & economic shifts
- Live market-moving news and insights, curated for you
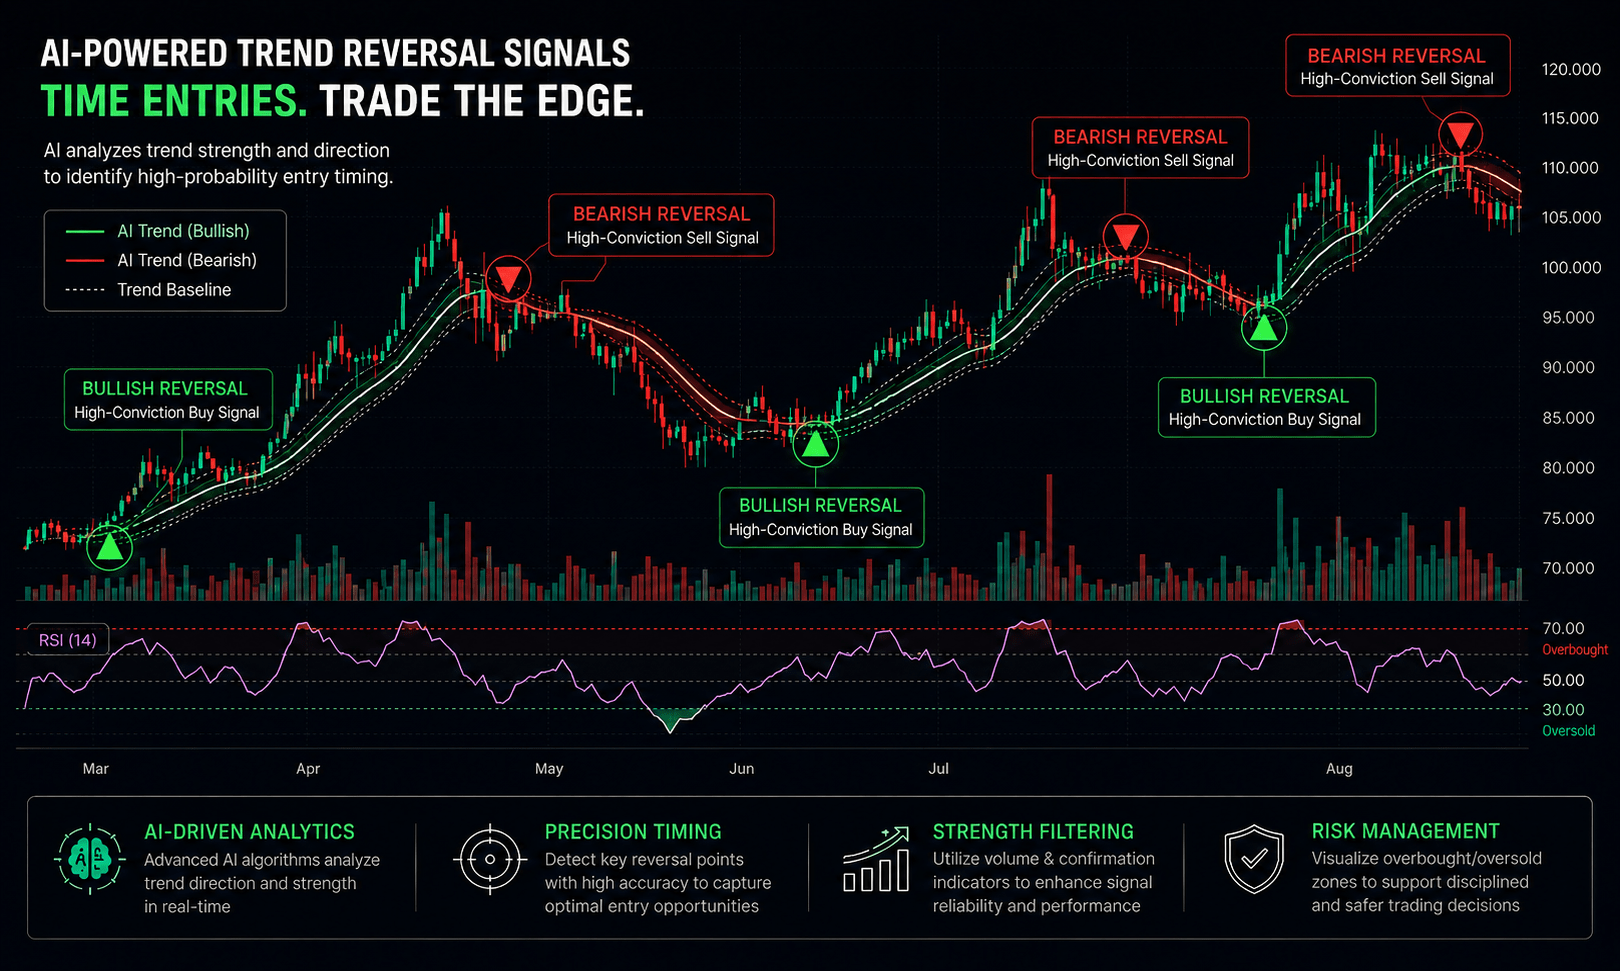
Bull Wave / Bear Wave Forecast Model
Engineered to help you read market direction and momentum faster than the crowd.
- Instantly separate bullish momentum from bearish pressure
- Pinpoint high-probability entry zones with confidence
- Chart signals clear enough for beginners, sharp enough for pros
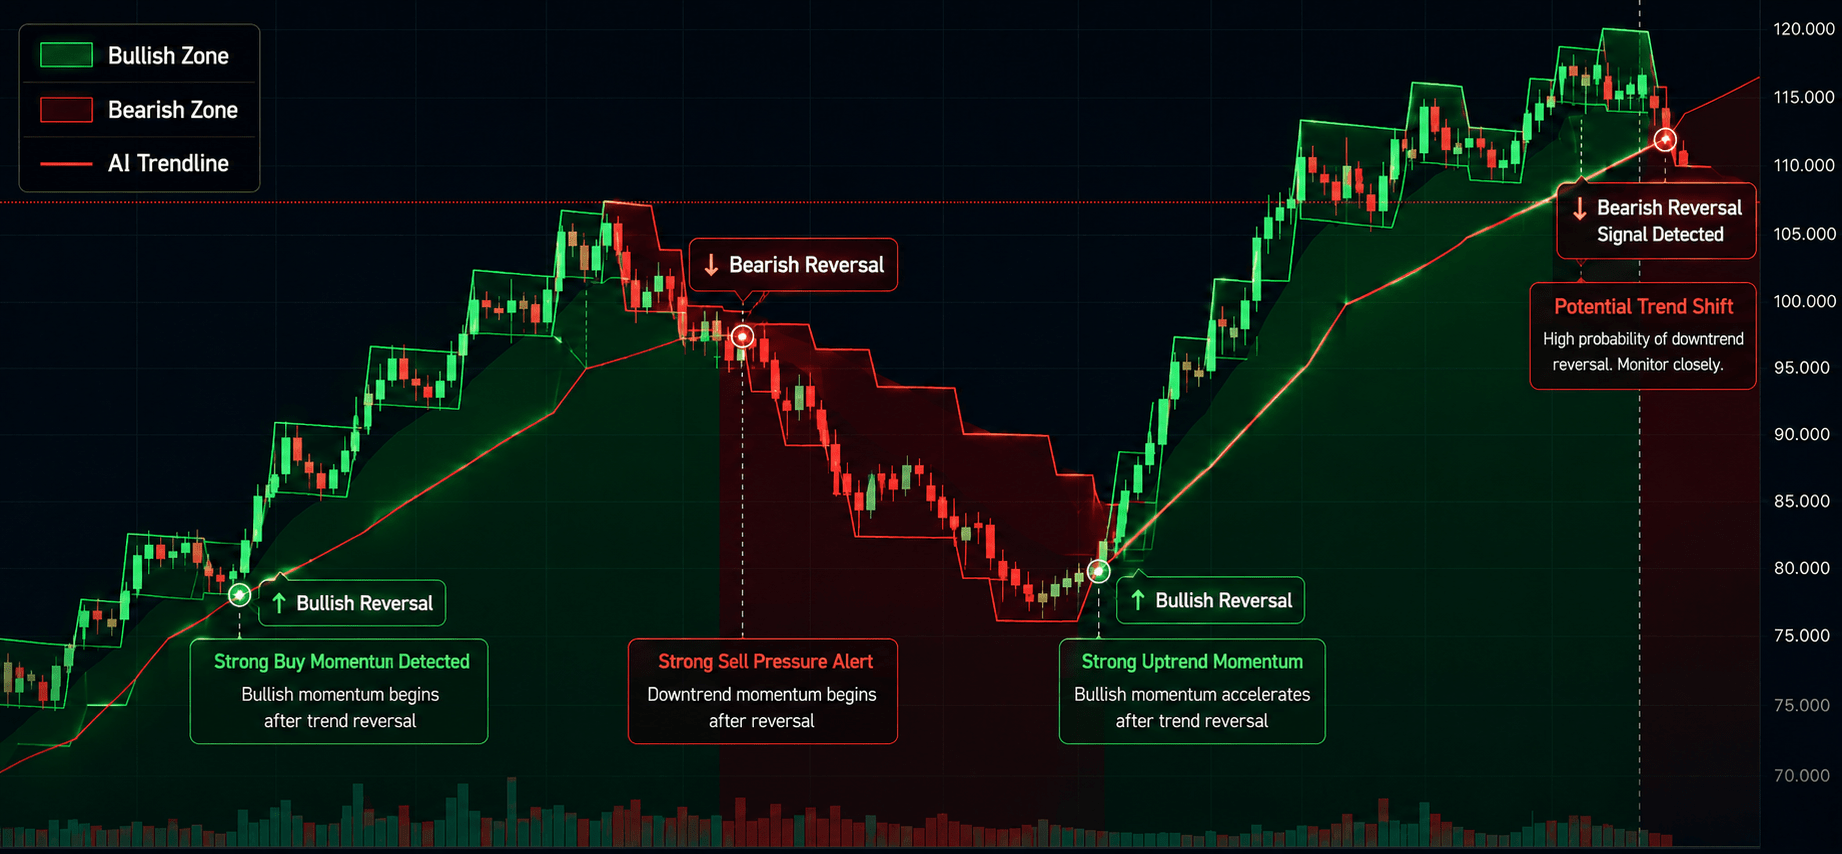
Winning Pattern Detection
Instantly surfaces the high-probability setups that repeat across the charts — a trusted edge for timing your entries and exits.
- Spot momentum building in real time
- Catch trend-reversal points before they break
- Built for active traders who need results, not theory
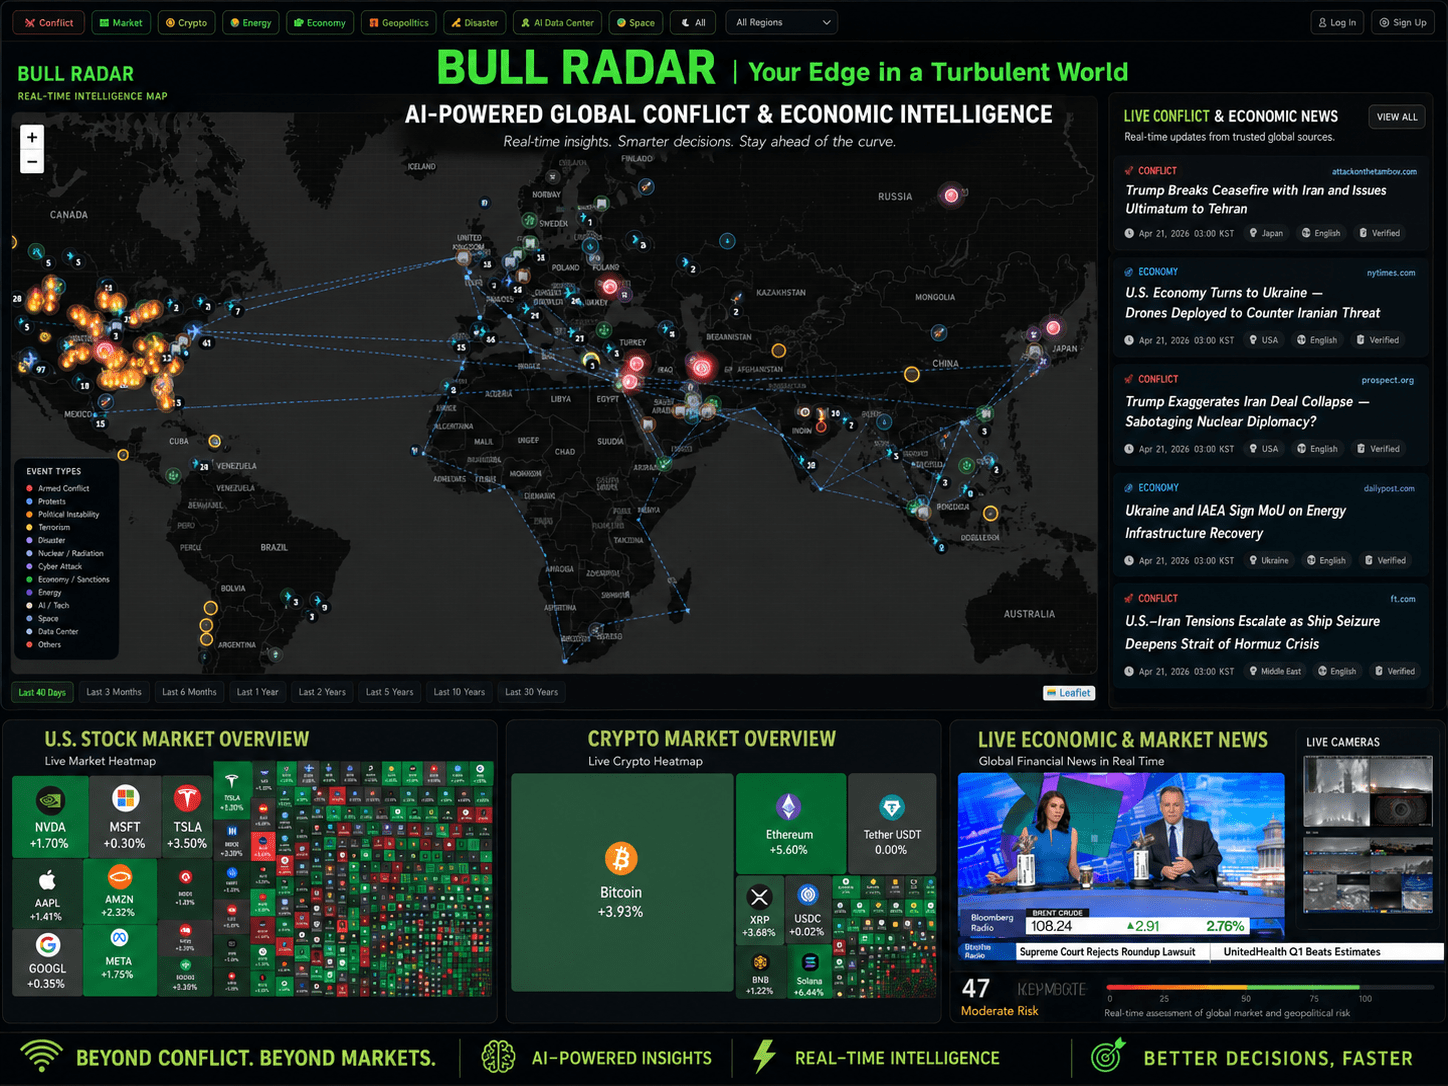
AI Live Economic Dashboard
AI analyzes real-time market data — turning complex, global investment flows into clear insight in seconds.
- Track global stock markets in real time
- See exactly which assets are strong — and which are fading
- Watch how geopolitical events move the markets
About the Author