Defining the Iron Condor
An iron condor is a four-leg options strategy that combines selling an out-of-the-money (OTM) put and call while simultaneously buying further OTM put and call options to cap potential losses. It is a market-neutral strategy that profits when the underlying stays within a defined price range through expiration.
The Four Legs
With the stock at $100, a trader might sell the $95 put and buy the $90 put for downside protection, while selling the $105 call and buying the $110 call for upside protection. The two sold (inner) options generate premium income, while the two bought (outer) options act as insurance limiting the maximum loss.
| Position | Strike | Role |
|---|---|---|
| Buy Put | 90 | Caps downside loss |
| Sell Put | 95 | Collects premium |
| Sell Call | 105 | Collects premium |
| Buy Call | 110 | Caps upside loss |
Worked Profit and Loss Example
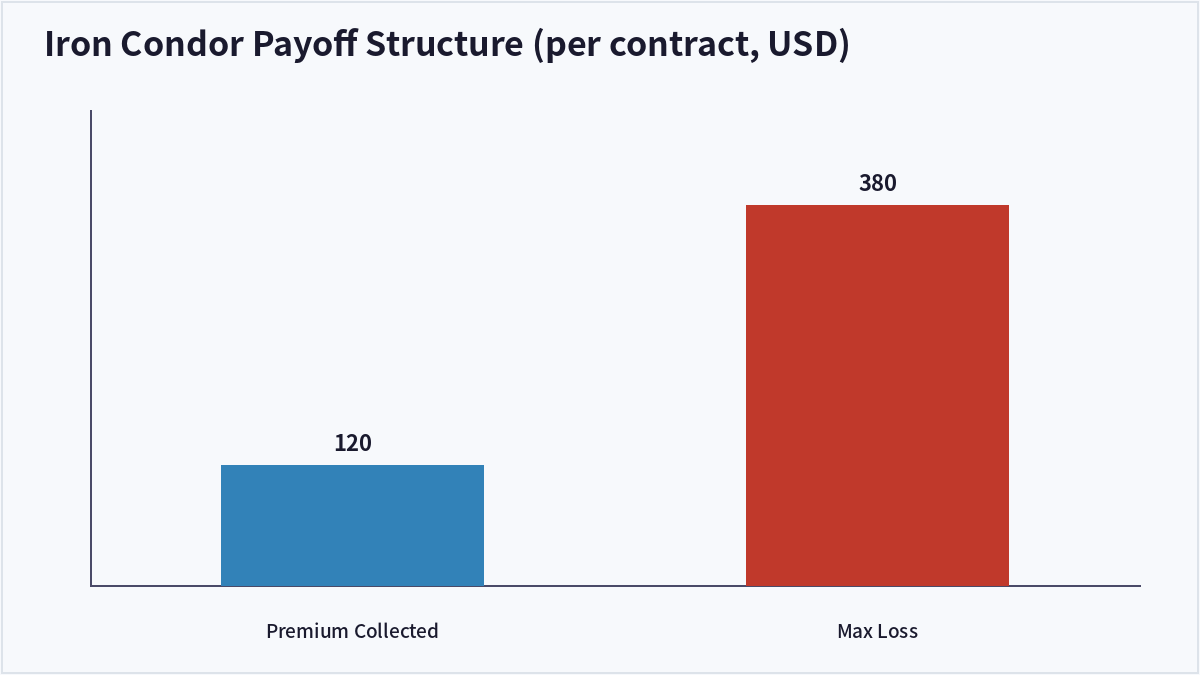
If the net premium collected is $1.20 per share ($120 per contract with the standard 100-share multiplier), the trade earns its full $120 max profit if the stock stays between $95 and $105 at expiration. If price moves beyond $90 or $110, the loss is capped at the $5 strike width minus the premium collected — $380 per contract.
When to Use an Iron Condor
This strategy works best when implied volatility (IV) is elevated relative to its historical average — meaning option premiums are rich — and a major catalyst (like earnings) has already passed, leaving expectations of a calmer, range-bound period ahead.
Managing the Risk
As the underlying price approaches either short strike, early assignment risk on that leg increases. Traders commonly close the entire position or roll the threatened side further out to avoid mounting losses as price challenges one of the short strikes.
Frequently Asked Questions
How is an iron condor different from an iron butterfly?
An iron condor spaces its short strikes apart for a wider profit zone but smaller premium, while an iron butterfly stacks both short strikes at the same near-the-money strike for a narrower profit zone but larger premium.
How is max loss calculated?
Max loss equals the wider of the two strike-width spreads, minus the net premium received, multiplied by the number of contracts and the option multiplier (typically 100).
Do you need to hold until expiration?
No — many traders close the position early, often around two to three weeks before expiration once 50-70% of maximum profit has been captured, to reduce gamma and assignment risk.
Is this a beginner-friendly strategy?
Because losses are defined upfront, it is relatively more manageable than uncapped option-selling strategies, but coordinating four simultaneous legs and understanding margin and assignment risk still requires some options trading experience first.
Key Takeaways
The iron condor sells inner OTM options for premium and buys outer OTM options to cap risk, profiting most when the underlying stays within the defined range through expiration. This article is for informational purposes only and does not constitute investment advice.

QuantPro: AI Finds the Trade Before You Do
From AI-powered chart analysis to real-time market intelligence — everything a serious investor needs, in one platform.
- Automated AI chart analysis with precision trend timing
- Bull Radar: real-time visualization of geopolitical & economic shifts
- Live market-moving news and insights, curated for you
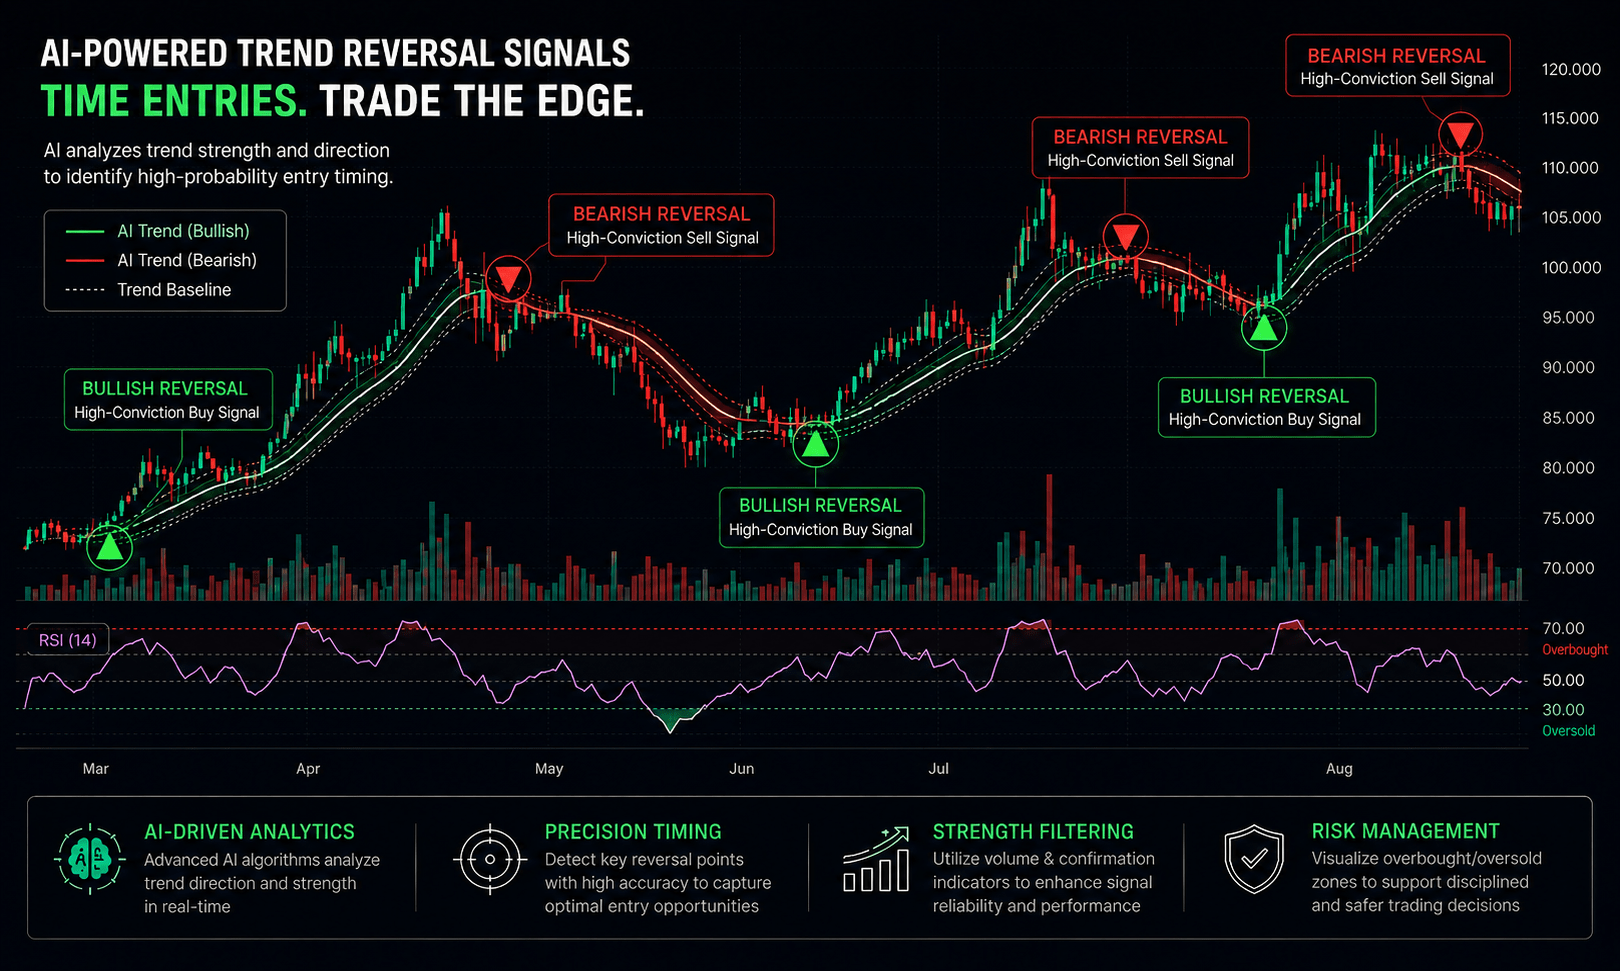
Bull Wave / Bear Wave Forecast Model
Engineered to help you read market direction and momentum faster than the crowd.
- Instantly separate bullish momentum from bearish pressure
- Pinpoint high-probability entry zones with confidence
- Chart signals clear enough for beginners, sharp enough for pros
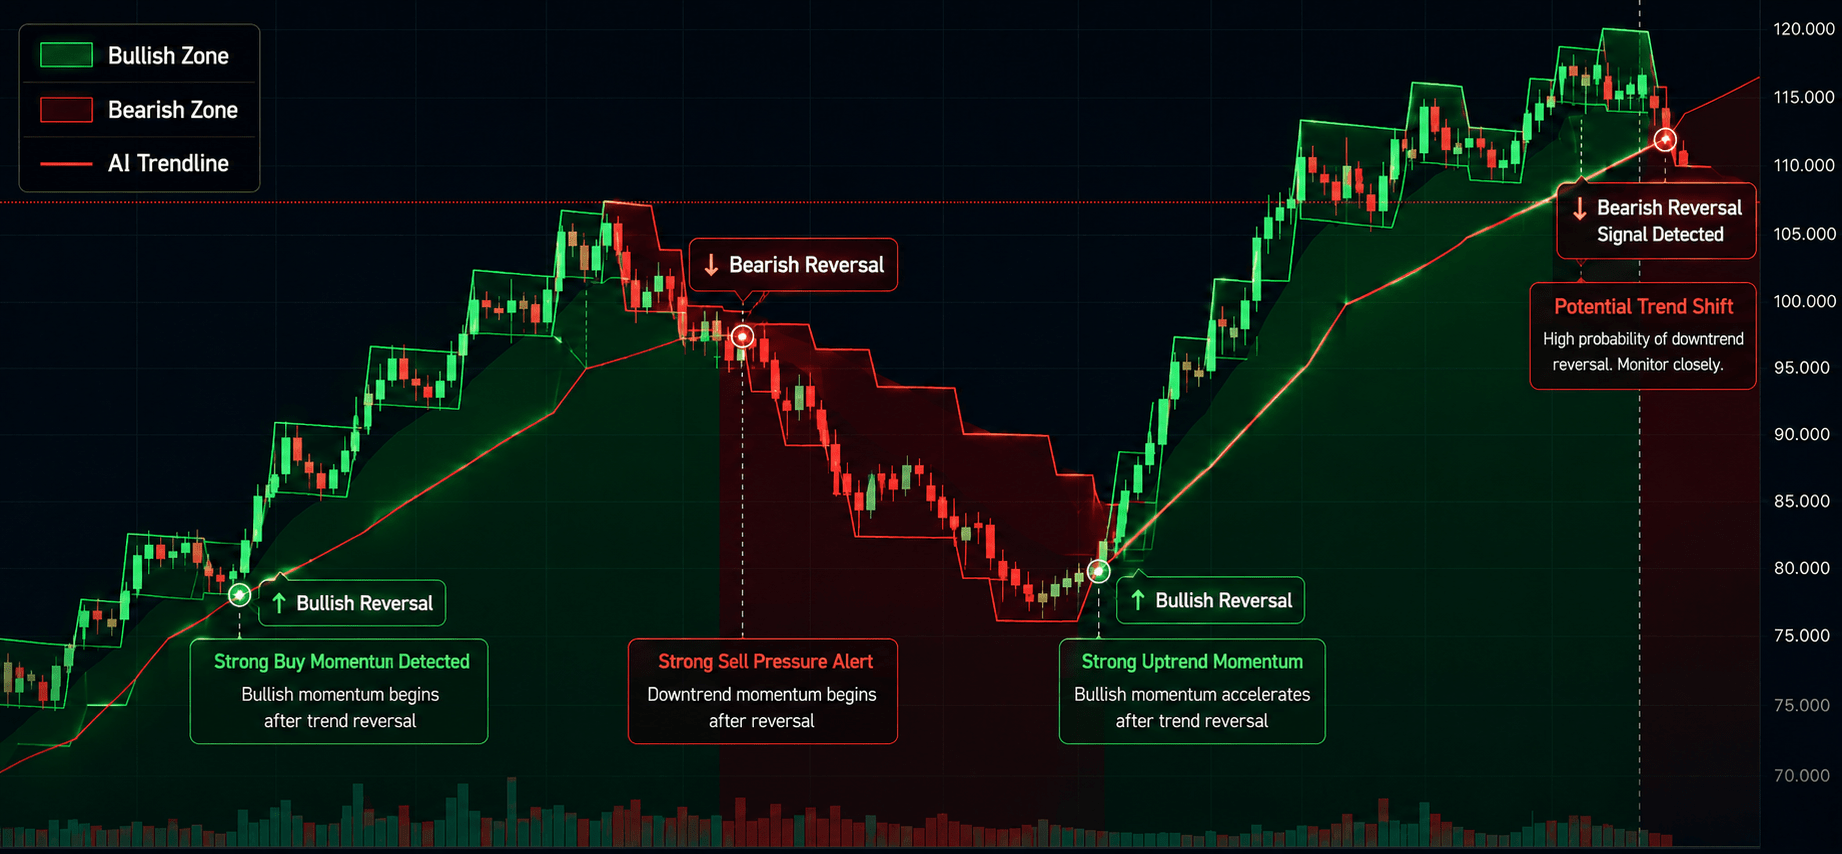
Winning Pattern Detection
Instantly surfaces the high-probability setups that repeat across the charts — a trusted edge for timing your entries and exits.
- Spot momentum building in real time
- Catch trend-reversal points before they break
- Built for active traders who need results, not theory
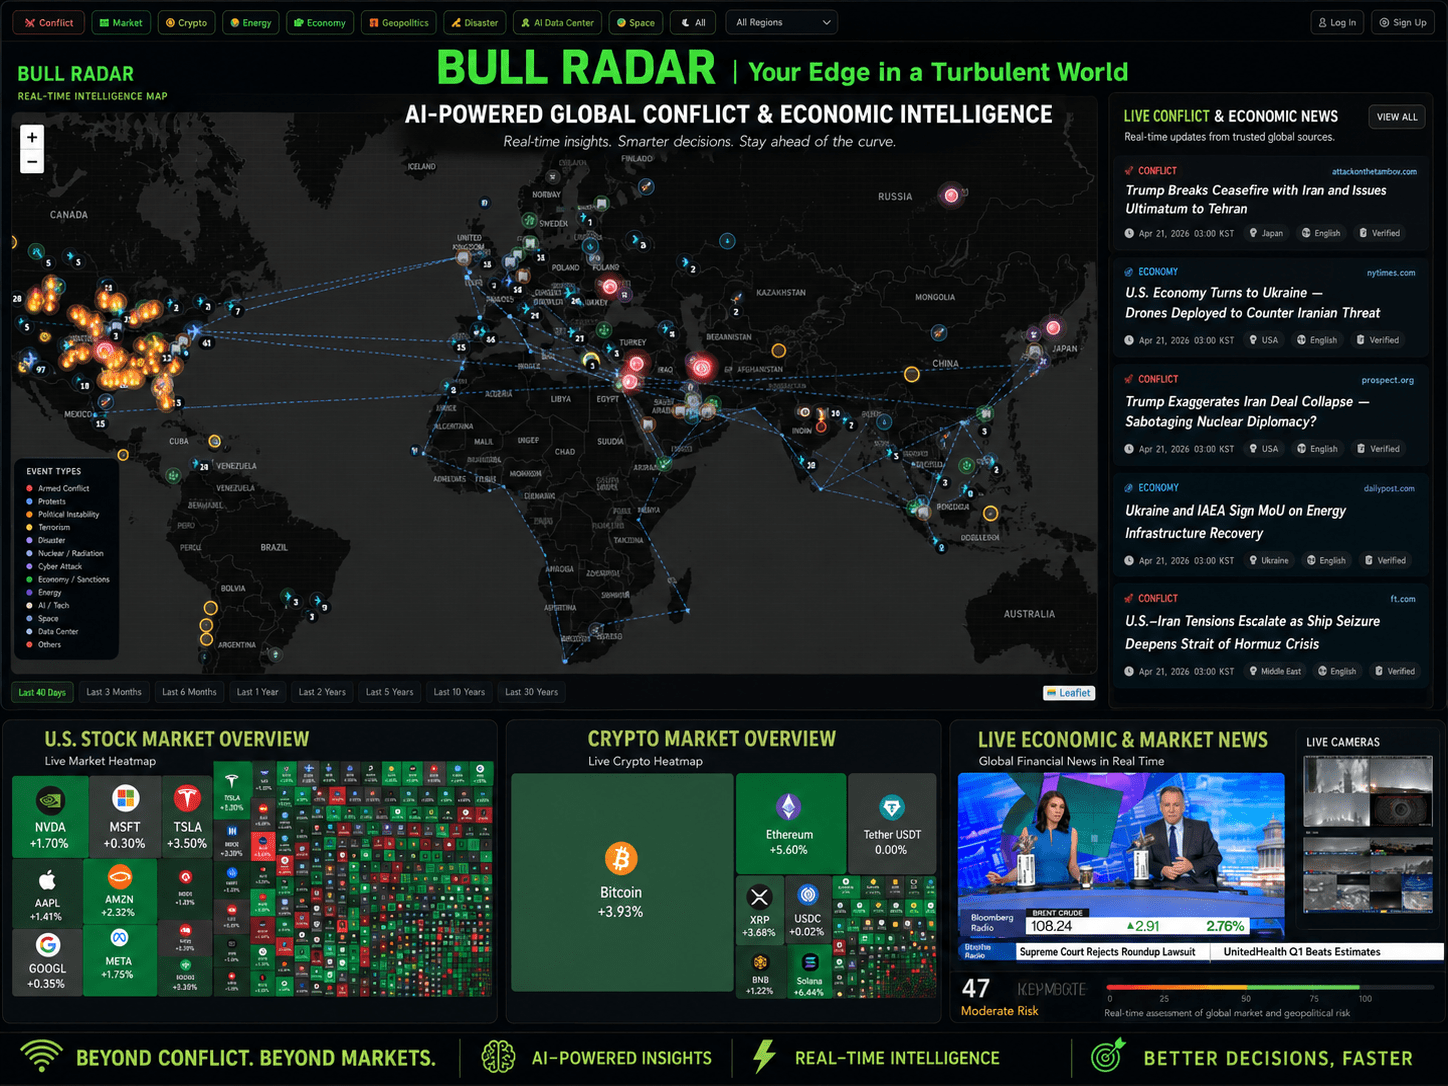
AI Live Economic Dashboard
AI analyzes real-time market data — turning complex, global investment flows into clear insight in seconds.
- Track global stock markets in real time
- See exactly which assets are strong — and which are fading
- Watch how geopolitical events move the markets
About the Author