What a Yield Curve Inversion Is
Under normal conditions, longer-maturity bonds carry higher yields than shorter-maturity ones because investors demand extra compensation for locking up money longer. A yield curve inversion occurs when this relationship flips — short-term yields rise above long-term yields — often because the central bank has pushed short-term rates up sharply, or because investors are buying long-term bonds in anticipation of future rate cuts. The most closely watched version compares the U.S. 10-year Treasury yield to the 2-year yield.
Why It’s Called a Recession Warning
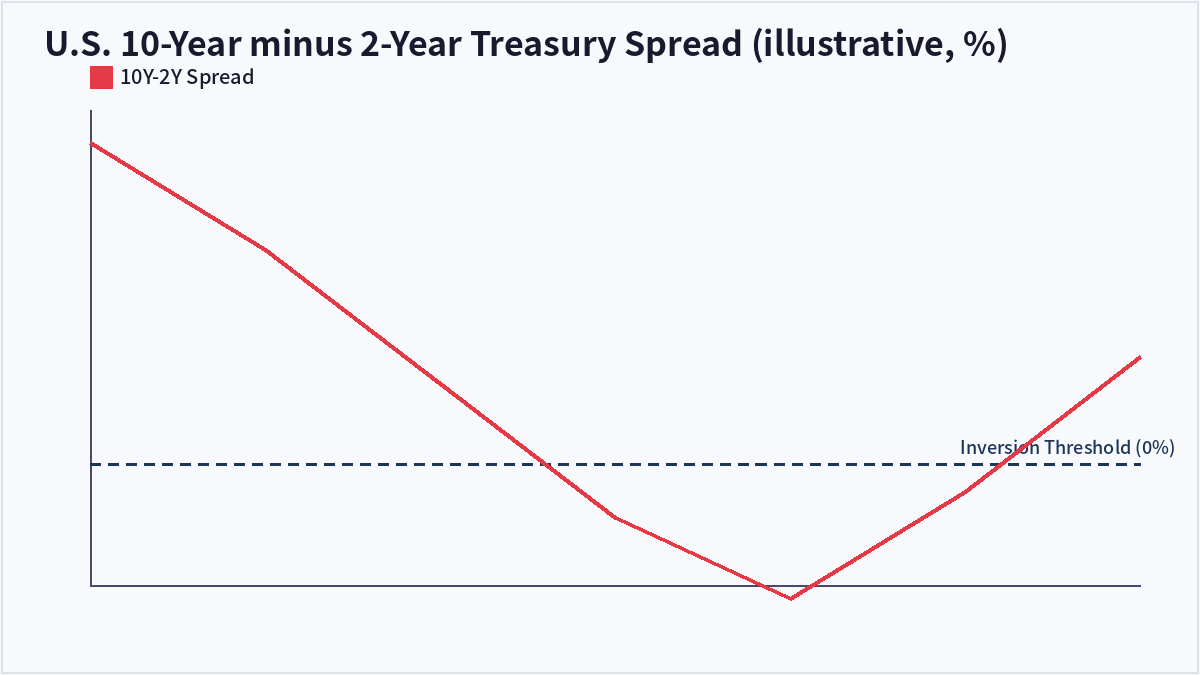
The 10-year/2-year inversion has preceded nearly every U.S. recession over the past several decades, which is why it draws so much market attention. The logic is that investors are effectively pricing in expectations of future rate cuts — a signal that the market anticipates the economy will slow enough to require monetary easing. However, the lag between inversion and an actual recession has historically ranged from several months to roughly two years, making it a poor short-term timing tool.
What Investors Should Keep in Mind
An inversion alone doesn’t guarantee a recession is imminent, and stocks have sometimes continued rising for a considerable period after the curve first inverted. Some analysts note that it’s actually the re-steepening of the curve — when the inversion resolves — that has often coincided more closely with the onset of an actual downturn. For this reason, the yield curve is best used alongside other indicators like employment and consumer spending data rather than as a standalone trading signal.
| Condition | Normal Curve | Inverted Curve |
|---|---|---|
| Yield relationship | Long-term > short-term | Short-term > long-term |
| Market expectation | Steady growth ahead | Future rate cuts, slower growth |
| Historical association | Economic expansion | Often precedes recession |
Frequently Asked Questions
Should I sell stocks as soon as the yield curve inverts?
Not necessarily — historically, equity markets have often continued to rise for months or even longer after an initial inversion, so the signal is better used as one input among several rather than an immediate trading trigger.
Why is the 10-year/2-year spread the most popular version?
The 10-year yield tends to reflect long-term growth and inflation expectations while the 2-year yield reflects near-term policy rate expectations, so comparing the two captures both monetary policy and growth outlook in a single, easily tracked number.
Does the yield curve un-inverting mean the danger has passed?
Not necessarily — in several past cycles, the curve re-steepening (returning to positive) has coincided closely with the actual onset of recession, so this transition deserves just as much attention as the initial inversion.
Do other countries’ yield curves also invert?
Yes, many countries’ government bond yield curves can invert based on their own monetary policy and growth expectations, and are often compared alongside U.S. Treasury yields to gauge the global macro picture.
Key Takeaways
A yield curve inversion occurs when short-term bond yields exceed long-term yields, and the 10-year/2-year spread in particular has historically preceded most U.S. recessions, though the lag before an actual downturn can be long and uneven. This article is for informational purposes only and does not constitute investment advice.

QuantPro: AI Finds the Trade Before You Do
From AI-powered chart analysis to real-time market intelligence — everything a serious investor needs, in one platform.
- Automated AI chart analysis with precision trend timing
- Bull Radar: real-time visualization of geopolitical & economic shifts
- Live market-moving news and insights, curated for you
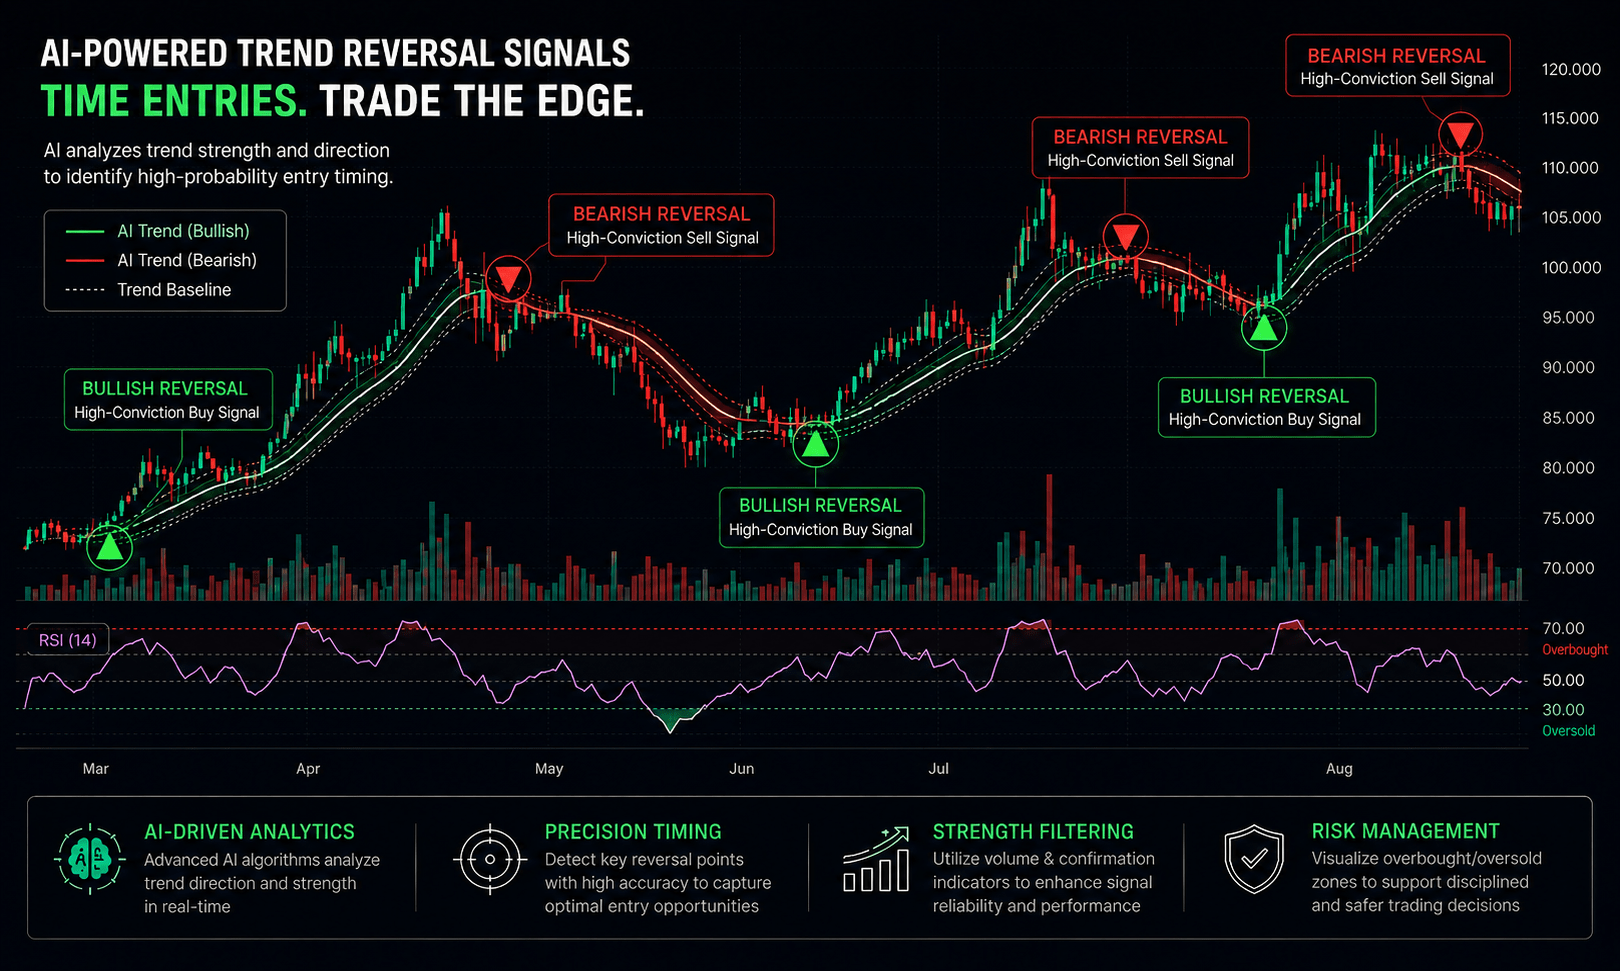
Bull Wave / Bear Wave Forecast Model
Engineered to help you read market direction and momentum faster than the crowd.
- Instantly separate bullish momentum from bearish pressure
- Pinpoint high-probability entry zones with confidence
- Chart signals clear enough for beginners, sharp enough for pros
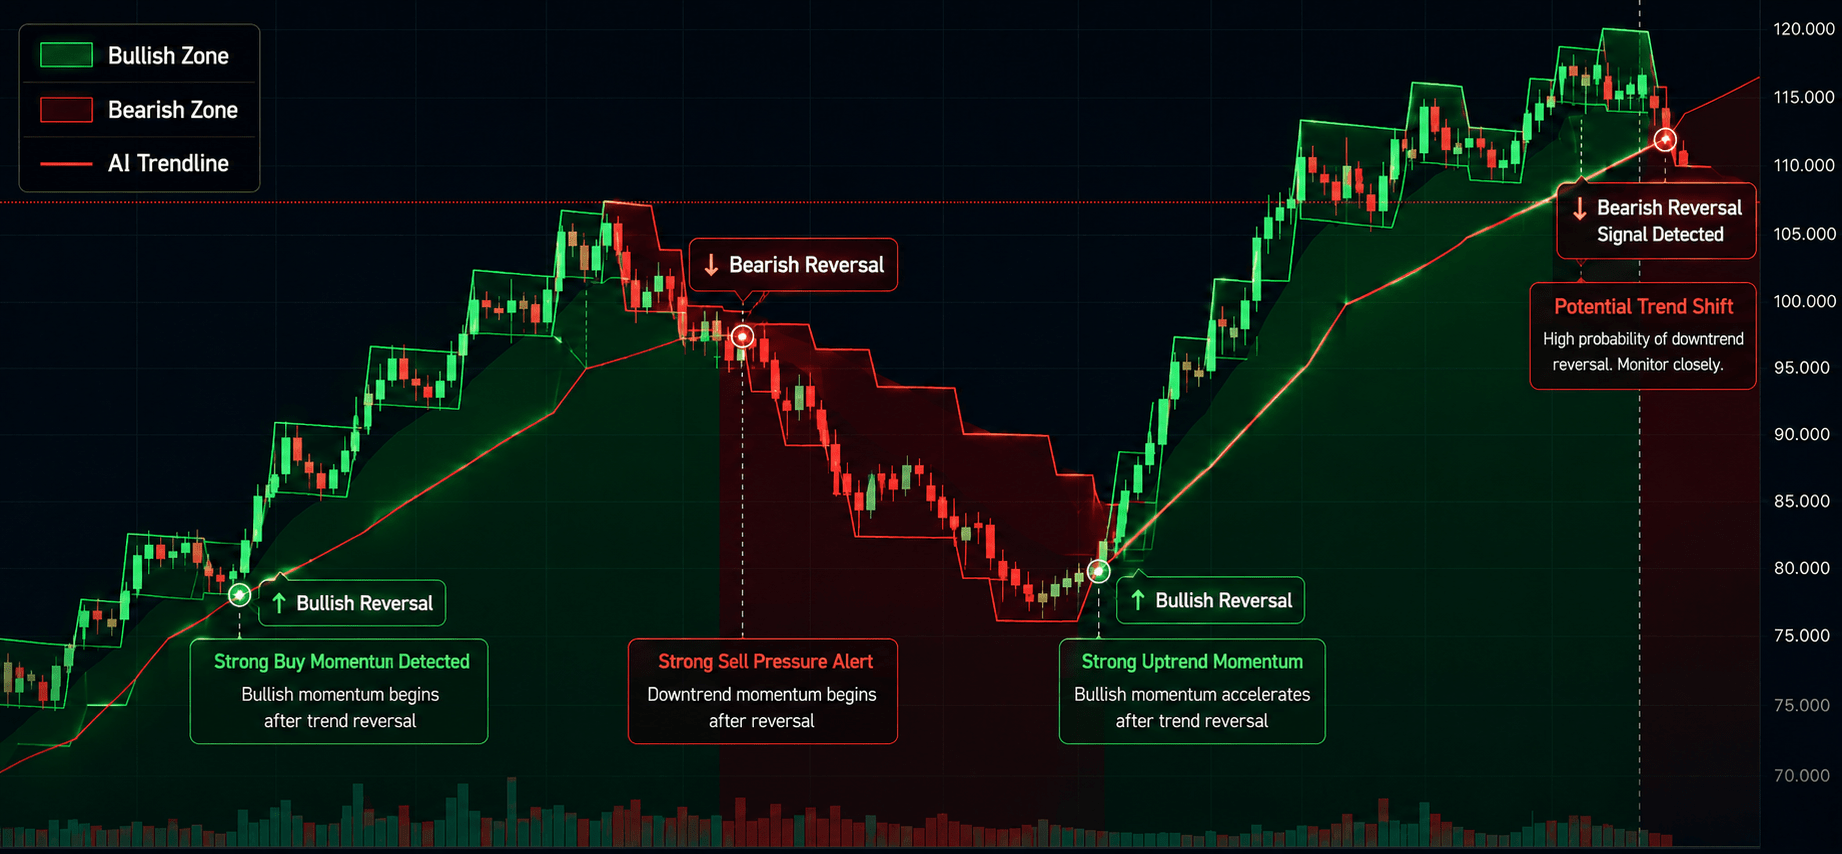
Winning Pattern Detection
Instantly surfaces the high-probability setups that repeat across the charts — a trusted edge for timing your entries and exits.
- Spot momentum building in real time
- Catch trend-reversal points before they break
- Built for active traders who need results, not theory
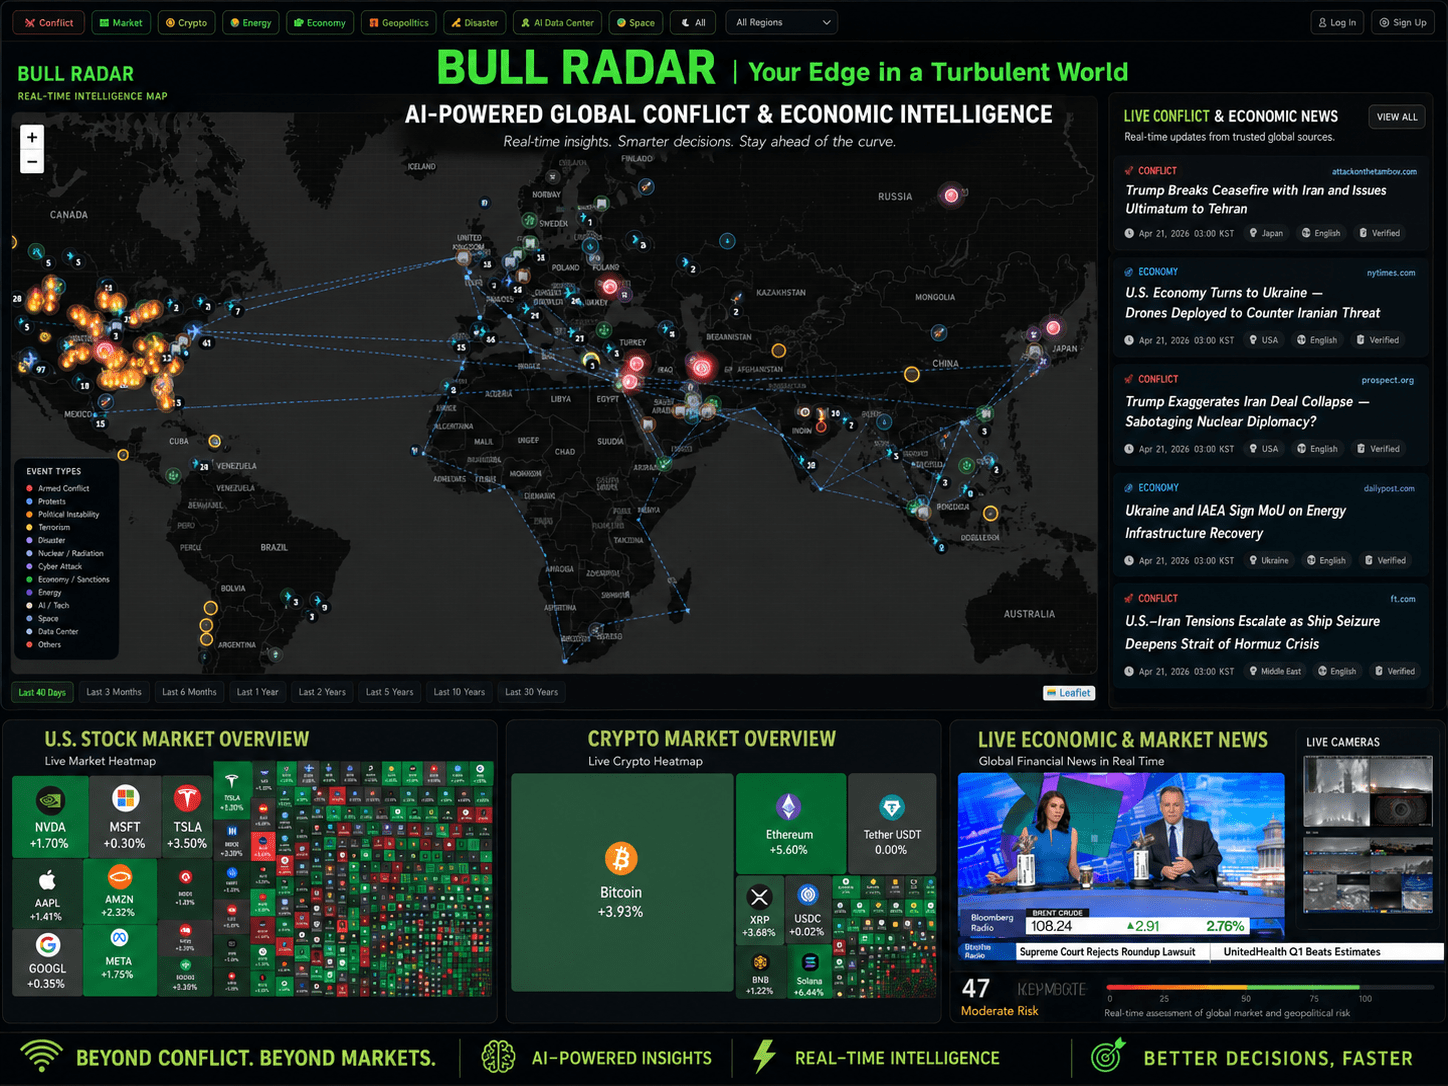
AI Live Economic Dashboard
AI analyzes real-time market data — turning complex, global investment flows into clear insight in seconds.
- Track global stock markets in real time
- See exactly which assets are strong — and which are fading
- Watch how geopolitical events move the markets
About the Author